
Blogs
PW Consulting: Wedding Dress Market Hits $186M in 2025, Projected 6.08% CAGR Through 2032
By pmarketresearch, 2026-09-15
Executive Overview: Strategic Imperatives in the Global Wedding Dress Market
The wedding dress market stands at a pivotal juncture in 2026. As consumer preferences shift towards personalization, sustainability, and experiential value, industry stakeholders must navigate a landscape defined by both resilient growth and intensifying competition. This comprehensive market research publication by PW Consulting offers a granular examination of the sector, designed to equip executives, investors, and strategic planners with the intelligence necessary to capitalize on emerging opportunities. The insights presented herein are not merely statistical aggregates; they represent a roadmap for navigating the complexities of supply chain dynamics, regional demand fluctuations, and competitive differentiation in the coming years.
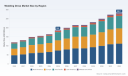
Our analysis covers the historical trajectory from 2020 through 2025, providing a robust baseline against which future projections are measured. The forecast period extends to 2032, allowing for long-term strategic planning. A central finding of this study is the projected Compound Annual Growth Rate (CAGR) of 6.08% during the forecast period. This indicates a sustained upward momentum, suggesting that the market is not only recovering from previous global disruptions but is also expanding beyond pre-pandemic benchmarks. The total market revenue is anticipated to reach significant milestones, surpassing the 280 million USD mark by the end of the forecast horizon, up from a base year value of 186.0 million USD in 2025. Such growth underscores the enduring cultural and economic significance of bridal wear, despite shifting demographics and economic pressures in various regions.
Market Trajectory and Growth Drivers
Understanding the velocity of market expansion is critical for capacity planning and investment allocation. The data indicates a consistent year-over-year increase in revenue, reflecting a market that is maturing yet still ripe for innovation. From a historical perspective, the sector demonstrated remarkable resilience, growing from 120.0 million USD in 2020 to 164.65 million USD by 2024. This recovery phase was characterized by a return to traditional ceremonies and a renewed appetite for conspicuous consumption in the bridal sector. As we move into 2026, the market size is projected to approximate 200.02 million USD, signaling a stabilization at higher valuation tiers.
Wedding Ring Market
The drivers behind this growth are multifaceted. Demographic shifts in key aging populations are being counterbalanced by rising marriage rates in emerging economies. Furthermore, the psychological shift towards "once-in-a-lifetime" spending, even amidst inflationary environments, supports the premiumization trend observed in recent quarters. However, growth is not uniform across all vectors. The industry is witnessing a bifurcation where mass-market availability competes with high-end bespoke services. Stakeholders must understand where their value proposition lies within this spectrum to optimize margin profiles. Our report delves into the specific catalysts fueling this expansion, including the rise of destination weddings, the influence of digitalmarketing on bridal retail, and the evolving lifecycle of wedding-related expenditures.
Structural Segmentation and Consumer Behavior
The architecture of the wedding dress market is defined by distinct segmentation channels that dictate go-to-market strategies. The report provides a detailed breakdown of the market by type, application, and region, offering clarity on where demand is concentrate d and how consumer behaviors diverge.
In terms of product type, the market is primarily split between off-the-rack solutions and customized offerings. While standardized inventory provides speed and accessibility, the customized segment represents a high-value opportunity for brands capable of delivering exclusivity. The data suggests a healthy equilibrium between these two streams, with each serving different consumer psychographics. Off-the-rack purchases appeal to cost-conscious and time-sensitive buyers, while customized gowns cater to those seeking unique design elements and a tailored fit. Understanding the margin implications and inventory risks associated with each type is essential for operational efficiency.
The application landscape further nuances this picture. Personal purchases remain the dominant force, driven by the bride's direct investment in her ceremony attire. However, the rental market constitutes a significant portion of revenue, reflecting a growing consciousness around sustainability and cost efficiency. Additionally, photographic studios represent a niche but steady demand channel, where dresses are purchased or rented specifically for imagery rather than ceremony use. Our analysis explores the elasticity of demand across these applications, helping businesses identify which customer segments offer the highest lifetime value and lowest churn risk.
Regional Dynamics and Global Supply Chains
Geography plays a decisive role in market performance. The report maps revenue distribution across major global regions, highlighting the disparities in market maturity and growth potential. North America continues to represent a substantial portion of global revenue, underpinned by a robust culture of elaborate wedding ceremonies and high disposable income levels. Europe follows as a mature market with strong historical ties to bridal fashion, characterized by a preference for luxury and heritage brands.
Wedding Dress Market
The Asia Pacific region presents a compelling growth story, driven by rising middle-class populations and the adoption of Western wedding traditions alongside local customs. Latin America and the Middle East and Africa regions, while currently smaller in total volume, offer high growth potential as economic conditions stabilize and the wedding industry professionalizes. For manufacturers and retailers, understanding these regional nuances is vital. Logistics costs, tariff structures, and local consumer preferences vary significantly. A strategy that works in North America may not translate directly to Eastern Europe or Southeast Asia. Our geographic analysis provides the context needed to tailor distribution networks and marketing messages to local realities without needing to rely on generic global assumptions.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment in the wedding dress market is fragmented yet features strong brand identities. Our research profiles a diverse array of key companies that define the current industry standards. These entities range from boutique American designers focusing on specific aesthetic niches to large-scale manufacturers based in Europe and Asia optimized for volume and wholesale distribution.
In the United States, the market is characterized by a strong presence of designer brands that emphasize American design and manufacturing. Companies such as Alyssa Kristin and Katherine Tash highlight the value proposition of domestic production, appealing to consumers who prioritize supply chain transparency and quality control. Similarly, brands like Anne Barge and Sareh Nouri focus on luxury bridal gowns, often produced in-house to maintain strict quality standards and design exclusivity. The high-end segment is further populated by established names like Vera Wang Bride and Morilee New York, which leverage iconic status to command premium pricing. Contemporary options are also well-represented by players like Justin Alexander and CINQ, who target the mid-to-high-end market with modern designs that resonate with younger demographics.
The competitive field extends beyond domestic boundaries. In Europe, Poland-based Pollardi Fashion Group stands out as one of the largest factories for wedding and evening dresses, indicating a strong manufacturing backbone in the region. Italy's Ricca Sposa maintains a position as a luxury bridal brand with significant wholesale presence, recently reinforcing its market visibility through participation in major industry events such as Barcelona Bridal Fashion Week in April 2026. In Asia, manufacturers like TEG (TEG Made) in China and Suzhou Leader Apparel Co., Ltd. provide premium bridalwear manufacturing services, catering to both branded labels and private label opportunities. Turkish manufacturer Metropol Wedding Dress and Chinese wholesaler BETANCY further illustrate the global supply chain's reliance on specialized manufacturing hubs capable of handling custom and wholesale volumes efficiently.
Recent developments highlight the proactive nature of these competitors. In 2026, several key players have intensified their presence at major trade shows and fashion weeks. Anne Barge introduced its Fall 2026 collection at New York Bridal Fashion Week in May 2026, signaling a continued commitment to seasonal innovation. Allure Bridals held designer events including Once Upon a Dress in May 2026, reinforcing its brand engagement strategy. These activities are not merely promotional; they are strategic moves to secure buyer relationships and dictate trend directions. Our report analyzes how these competitive tactics influence market share and brand equity, providing a framework for assessing rival strategies.
Industry Context and Recent Developments
The operational context of the wedding dress market in 2026 is shaped by a combination of supply chain recalibration and consumer sentiment shifts. The industry is moving towards greater transparency and sustainability, a trend reflected in the product offerings of brands like LEIN, which focuses on sustainable and modern wedding dresses. This shift is not superficial; it impacts material sourcing, production timelines, and end-of-life considerations for garments. Companies that fail to adapt to these ethical expectations risk alienation from a growing segment of conscientious consumers.
Furthermore, the frequency of industry gatherings and collection launches remains high. The participation of companies like Ricca Sposa and Kaya Wedding in European and Barcelona bridal events during April 2026 underscores the importance of physical presence in building B2B and B2C relationships. These events serve as bellwethers for upcoming trends and color palettes. For market entrants or existing players looking to pivot, monitoring these calendars is essential. The data compiled in this study includes timelines of such key events and product launches, allowing strategists to align their own release cycles with market peaks.
Strategic Value of This Research
Access to granular data is the differentiator between reactive management and proactive strategy. This report is structured to provide actionable intelligence rather than abstract observations. It empowers stakeholders to identify white space opportunities, assess competitor vulnerabilities, and optimize pricing strategies. By integrating historical data with forward-looking projections, the document serves as a foundational tool for budgeting, hiring, and expansion planning.
The depth of segmentation analysis allows for precise targeting. Whether a company is looking to expand its rental inventory, invest in customized manufacturing capabilities, or enter a new geographic region, the data supports evidence-based decision-making. The competitive profiling extends beyond basic company descriptions to include an assessment of their offerings and recent strategic moves, enabling a clearer picture of the battlefield. Understanding the concentration of market power, reflected in the competitive metrics, helps in gauging the barrier to entry and the potential for consolidation.
Conclusion and Next Steps
The wedding dress market in 2026 offers a complex array of opportunities for those equipped with the right intelligence. Growth is sustained, but the path to capturing value requires a nuanced understanding of segmentation, regional dynamics, and competitive behavior. PW Consulting's detailed market research provides the comprehensive view necessary to navigate this environment successfully.
For executives and strategists who require the full depth of this analysis, including detailed segmentation splits, specific regional revenue figures, and exhaustive competitor matrices, we invite you to access the complete report. The executive summary provided here illustrates the scope and strategic relevance of the findings, but the full document contains the specific data points required to finalize investment cases and operational plans. Engage with the full dataset to transform industry insights into tangible business outcomes.
For detailed analysis of this topic, please visit the official page: Wedding Dress Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Electric Scooters Market Hits $38.23B in 2025, Forecasts 9.81% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Horizons for the Electric Scooter Market: Navigating Growth Through 2032
The urban mobility landscape is undergoing a seismic shift, driven by the dual imperatives of decarbonization and last-mile efficiency. Electric scooters, once viewed as niche recreational devices, have matured into integral components of the global transportation ecosystem. For stakeholders operating within this dynamic sector, understanding the trajectory of market expansion is not merely an exercise in forecasting it is a prerequisite for strategic positioning. Our latest comprehensive market research on the Electric Scooter Market offers a granular examination of the forces shaping industry outcomes from 2026 through 2032, providing executives, investors, and policymakers with the intelligence needed to navigate an increasingly complex competitive environment.
Electric Scooters Market
This analysis is built upon a rigorous evaluation of historical performance spanning 2020 to 2025, extending forward through a seven-year forecast period. The data reveals a market characterized by robust structural momentum, with a compound annual growth rate of 9.81 percent projected across the evaluation window. This sustained upward trajectory reflects deepening consumer adoption, expanding commercial deployment, and the convergence of supportive regulatory frameworks with technological maturation. Yet beneath these headline figures lies a far more intricate reality, one defined by regional asymmetries, product segmentation shifts, and intensifying competitive pressures that demand nuanced strategic responses.
Market Trajectory and Core Dynamics
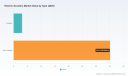
The electric scooter sector has demonstrated remarkable resilience and expansion potential over the past half-decade. Revenue valuations have progressed from a baseline of 24.32 billion USD in 2020, climbing through successive growth phases to reach 38.23 billion USD by 2025. This historical arc establishes a credible foundation for near-term projections, with valuations anticipated to breach 41.58 billion USD in 2026 and continue their ascent toward 73.5 billion USD by 2032. Such growth is neither accidental nor uniform. It emerges from the interplay of urbanization pressures, infrastructural investments, evolving consumer preferences, and the strategic maneuvering of manufacturers seeking to capture share within an increasingly crowded arena.
Several macro force are propelling this expansion. Urban congestion in megacities has accelerated demand for compact, zero-emission alternatives to traditional motorized transport. Municipalities worldwide are integrating micromobility into broader transit networks, recognizing the role that electric scooters play in bridging gaps between mass transit hubs and final destinations. Simultaneously, advancements in battery chemistry, motor efficiency, and connected vehicle technologies have elevated product reliability and user experience, addressing earlier adoption barriers related to range anxiety and maintenance complexity.
However, growth is not without friction. Regulatory interventions have introduced new layers of complexity for market participants. Trade policy adjustments, including the imposition of significant tariffs on electric scooters imported from China, have reshaped supply chain considerations and prompted manufacturers to reevaluate sourcing strategies and regional production footprints. Concurrently, evolving standards governing lithium-ion battery transport, storage, and recycling impose compliance obligations that influence product design, logistics, and total cost structures. These dynamics underscore the necessity of proactive regulatory intelligence as a core competency for organizations operating in this space.
Segmentation Architectures and Demand Drivers
A superficial glance at aggregate market figures obscures the divergent growth patterns unfolding across product categories, end-use verticals, and geographic corridors. Understanding these sub-market dynamics is essential for allocating capital efficiently, tailoring product roadmaps, and identifying white-space opportunities that remain underserved by current competitive offerings.
Product architecture continues to bifurcate between foldable and non-foldable designs, each addressing distinct user requirements and deployment contexts. Foldable configurations prioritize portability and multi-modal integration, appealing to commuters who combine scooter usage with public transit. Non-foldable variants, by contrast, emphasize structural robustness, payload capacity, and extended range, catering to applications where stability and durability outweigh portability concerns. The relative performance of these segments reflects broader shifts in consumer lifestyle patterns and commercial fleet requirements, with implications for manufacturing specialization and inventory strategy.
Application-wise, the market divides between personal use and commercial deployment, each following distinct adoption curves and value propositions. Personal use remains anchored in consumer preference for convenient, low-cost, environmentally conscious mobility solutions. Commercial applications, spanning last-mile delivery fleets, shared micromobility programs operated by municipal authorities or private operators, and corporate campus transportation, introduce additional dimensions of scale, utilization efficiency, and total cost of ownership. The interplay between these application verticals shapes demand volatility, pricing architecture, and the extent to which manufacturers can pursue differentiated value chains.
Geographically, market performance varies substantially, reflecting differences in urban density, regulatory environments, infrastructure maturity, and cultural acceptance of micromobility. Certain regions exhibit accelerated penetration rates driven by aggressive public-sector support and dense urban form, while others progress more incrementally as infrastructure catch-up and consumer education remain ongoing processes. These spatial divergences create heterogeneous opportunity landscapes, requiring market entrants and incumbents alike to calibrate their regional strategies with precision rather than relying on one-size-fits-all expansion models.
Competitive Landscape: Navigating an Increasingly Crowded Field
The electric scooter market is defined by a concentration of established players alongside a steady influx of new entrants, each leveraging distinct technological capabilities, brand positioning, and operational models to capture share. Our research maps this competitive terrain in detail, examining the strategic postures of leading manufacturers and shared mobility operators whose actions collectively shape market direction.
Among the prominent hardware manufacturers, several Chinese-based companies have built formidable portfolios emphasizing range, connectivity, and performance versatility. Segway-Ninebot continues to expand its E-series and Max series offerings, with recent product introductions at CES 2026 highlighting updated battery technologies and cross-platform integration between e-bikes and e-scooters. NIU International has reinforced its position through the KQi series and lightweight variants that blend integrated connectivity with extended range options tailored for urban environments. Yadea Technology Group broadens its footprint by spanning electric two-wheeler scooters and motorcycles, leveraging advanced battery and motor systems that serve both personal and commercial end markets. Kaabo has carved a niche in the heavy-duty off-road segment, deploying high-capacity batteries and high-output motors that appeal to enthusiasts and specialized commercial users alike.
The Indian market has emerged as a particularly dynamic theater of innovation and scale. TVS Motor Company has continued to refine its Orbiter and Star Series e-scooters, with the 2026 release of the TVS X model introducing ABS options and updated powertrain configurations aimed at mainstream commuting segments. Ather Energy has pursued a differentiated strategy centered on AI-optimized performance, swappable battery architectures, and telematics integration, positioning its Rizta and 450X models as technology-forward solutions for urban and last-mile transport. Ola Electric has scaled rapidly with its S1 Pro and S1 X scooters, emphasizing high-efficiency motors and fast-charging infrastructure designed to support both personal ownership and fleet applications. These Indian players benefit from a confluence of domestic demand, manufacturing scale, and aggressive product iteration that collectively intensifies competitive pressure across the broader market.
In North America, a diverse set of manufacturers and operators addresses varying consumer and institutional requirements. Apollo Scooters and Gotrax serve commuter segments with solid-tire designs, extended battery life, and foldable configurations that balance affordability with reliability. Navee and VMAX have targeted higher-performance use cases, emphasizing 48V systems, hub-motor configurations, and range specifications that support daily transport and off-road capabilities. InMotion focuses on rugged terrain and payload capacity through high-peak-power models. LexGo has introduced dual-motor options that extend range and performance envelopes for urban and highway commuting contexts. These regional players operate within a regulatory environment shaped by evolving customs policies and battery transport standards, making supply chain agility and compliance readiness critical differentiators.
The shared mobility segment introduces an additional competitive dimension, with operators such as Lime, Bird, Spin, Veo, and Gogoro deploying dockless or fleet-based models tailored to citywide micromobility programs and municipal partnerships. These companies emphasize utilization efficiency, battery-swapping ecosystems, and customized fleet solutions that align with urban transportation authority requirements. Their competitive calculus differs from hardware manufacturers, prioritizing operational economics, regulatory relationships, and user acquisition over unit sales volume.
Market concentration data indicates that a relatively small number of firms command a substantial share of aggregate revenue, with CR3 and CR5 metrics reflecting meaningful consolidation at the top of the competitive pyramid. This concentration does not eliminate opportunities for specialized entrants, particularly those that can differentiate through technology, regional focus, or niche application expertise, but it does raise the stakes for market participants seeking to achieve scale and defend margins.
Regulatory and Supply-Side Currents
Strategic decision-making in the electric scooter market must account for a broad array of externalities that influence costs, product design, market access, and competitive dynamics. Regulatory frameworks are evolving rapidly across jurisdictions, and the implications extend far beyond compliance checklists.
Trade policy has emerged as a particularly salient factor. Recent tariff measures imposed on electric scooters imported from China, coupled with duties on lithium-ion battery components, have compelled manufacturers and distributors to reassess sourcing strategies, pricing architecture, and regional assembly considerations. Organizations that have developed flexible supply chain models, localized production capabilities, or diversified sourcing portfolios are better positioned to absorb policy-driven cost pressures while maintaining competitive pricing.
Battery-related regulations introduce additional complexity. Updated guidance on lithium battery marking, watt-hour rating requirements, and quantity limits for batteries packed with equipment impose new documentation and packaging obligations that influence logistics, warehousing, and cross-border movement. In parallel, recycling mandates in certain jurisdictions require elevated material recovery rates for battery components used in shared fleets, affecting total lifecycle costs and incentivizing investments in closed-loop material management.
Raw material dynamics further complicate the supply-side picture. Surging export volumes and values for lithium batteries reflect robust global demand for energy storage and electrified mobility, but they also introduce volatility considerations related to commodity pricing, capacity allocation, and geopolitical factors. Manufacturers that have secured long-term supply agreements, invested in battery technology differentiation, or developed partnerships with experienced component suppliers gain relative advantage in navigating these fluctuations.
Trip data collection and urban mobility monitoring efforts by transportation authorities provide increasingly granular visibility into usage patterns, trip lengths, and modal substitution effects. Access to such data, whether through public reporting or proprietary partnerships, enables operators and manufacturers to refine product specifications, optimize fleet deployment, and tailor marketing strategies to evidence-based usage insights rather than assumption-driven planning.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
This market research report is designed to translate complex market signals into structured, actionable intelligence. Beyond high-level sizing and growth projections, the analysis provides a detailed operational framework that supports strategic planning across multiple functional domains.
The report examines historical performance and forward-looking forecasts across the full evaluation period, grounding projections in transparent methodology while identifying inflection points, risk factors, and catalyst events that could alter trajectory. Segmentation analysis disaggregates demand by product architecture and application vertical, revealing where growth is accelerating, where saturation may emerge, and where unmet needs create openings for informed market entry. Geographic analysis maps regional performance differentials without reducing them to simplistic rankings, instead exploring the structural drivers that underpin divergent outcomes and the strategic implications for market access, partnership selection, and capacity deployment.
Hoverboard Scooters Market
Competitive profiling extends beyond descriptive summaries to assess strategic positioning, product portfolio coherence, recent launch activity, and the manner in which leading firms are responding to regulatory and supply-side pressures. Recent developments, including product introductions at major trade exhibitions, model refreshes targeting specific performance or range thresholds, and the expansion of model lineups by emerging brands, are contextualized within broader competitive dynamics to illustrate how incumbents and challengers are contesting market share.
Regulatory and supply-chain analysis is integrated throughout rather than treated as a standalone appendix, ensuring that decision-makers understand how policy developments, battery standards, recycling mandates, and trade measures interact with pricing, product design, and market entry timing. This integrated approach enables organizations to evaluate not only what the market is likely to do, but also where constraints and enablers will shape the feasible set of strategic choices.
For corporate strategists, the research supports scenarios around capacity investment, product portfolio optimization, and geographic prioritization. For investors, it provides a framework for assessing market attractiveness, competitive durability, and the risk-adjusted return profiles associated with different segments and regions. For policy-oriented readers, it illuminates the relationship between regulatory design, infrastructure development, and market outcomes, offering evidence that can inform program design and stakeholder coordination.
Conclusion: Prioritizing Precision in a High-Growth Market
The electric scooter market presents a compelling growth narrative, but growth alone does not guarantee competitive success. Organizations that thrive in this environment will be those that combine macro-level appreciation of market momentum with micro-level understanding of segmentation dynamics, competitive behavior, regulatory exposure, and supply-chain resilience. Aggregate figures provide necessary context, but they do not substitute for the granular intelligence required to allocate resources efficiently, position products effectively, and anticipate shifts before they become industry consensus.
This report offers that depth. It is structured to equip decision-makers with a comprehensive view of where the market stands, how it is evolving, and what strategic options are most likely to yield durable advantage through 2032. To access the full dataset, detailed segmentation breakdowns, regional performance analysis, competitive benchmarking, and the complete set of forecasts underpinning this analysis, we invite you to explore the full report on our platform. The complete intelligence package provides the precision necessary to convert market opportunity into executable strategy.
For detailed analysis of this topic, please visit the official page: Electric Scooters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Photomask Market to Hit $5.9B by 2032 with 5.8% CAGR
By pmarketresearch, 2026-09-15
Navigating the Next Frontier: Strategic Insights into the Semiconductor Photomask Market (2026-2032)
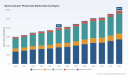
The semiconductor photomask market stands at a critical inflection point. As the foundational templates for lithography—the process that transfers circuit designs onto silicon wafers—photomasks are the unsung enablers of every advanced chip, from high-performance computing to next-generation displays. In 2025, the global photomask market reached an estimated $4,010 million, reflecting a steady upward trajectory from the $3,000 million recorded in 2020. Looking ahead, our latest research pegs the industry to surpass $5.9 billion by 2032, growing at a compound annual growth rate of 5.8 percent across the forecast period. These figures do more than chart revenue; they map the architectural backbone of a technology ecosystem under intense geopolitical, technological, and supply chain pressure.
For corporate strategists, investment committees, and procurement leaders, understanding why this market is expanding—and where the friction points lie—is no longer optional. This article serves as a strategic preview of our comprehensive Semiconductor Photomask Market research, outlining the analytical framework, competitive intelligence, and operational playbooks embedded in the full report. We invite you to explore how deep segmentation, scenario modeling, and regulatory mapping can transform high-level market awareness into actionable 2026 decision-making.
The Macro Trajectory: A Decade of Compound Growth Amid Structural Shifts
The historical data from 2020 through 2025 reveals a market that has proven remarkably resilient despite global chip shortages, capacity bottlenecks, and shifting demand cycles. Annual revenues climbed from $3,000 million in 2020 to $3,454.85 million in 2022, then accelerated further to $3,606.03 million in 2023 and $3,729.34 million in 2024. The $4,010 million baseline in 2025 underscores a structural acceleration rather than a cyclical rebound. Forecasts extend this momentum through 2032, projecting steady year-over-year gains that place the market well above $5,500 million by the end of the decade.
A 5.8 percent CAGR may appear measured against the explosive growth of some AI-driven semiconductor segments, but in the photomask world, it reflects something more profound: sustained capital expenditure in advanced logic and memory fabs, the proliferation of high-resolution display manufacturing, and the gradual migration of mature-node production into newer geographies. Our report dissects this trajectory across multiple dimensions, revealing where growth is concentrated, which application verticals are outpacing the baseline, and how product mix evolution is reshaping vendor economics. The narrative is not monolithic; it is a mosaic of converging demand signals that require precise navigation.
Navigating Regulatory Currents and Supply Chain Realities
No strategic assessment of the photomask industry in 2026 is complete without addressing the regulatory and supply chain environment. The landscape has grown increasingly complex, with policy interventions and material constraints actively reshaping cost structures, lead times, and geographic sourcing strategies.
On the regulatory front, the United States has intensified its focus on semiconductor supply chain security. A February 2025 executive order imposed a 25 percent tariff on semiconductors originating from China, a move that rippled through the broader electronics manufacturing ecosystem. By January 2026, the U.S. Commerce Department escalated its scrutiny with a proposed Section 232 investigation targeting semiconductor products, explicitly including photomask blanks. These actions occur alongside sustained dialogue between industry bodies and government agencies; for instance, the Semiconductor Industry Association submitted formal comments to the Bureau of Industry and Security in May 2025, addressing export controls and supply chain resilience.
Simultaneously, the U.S. CHIPS and Science Act has unlocked more than $52 billion in federal grants and tax incentives since its inception, catalyzing new fabrication capacity and, by extension, demand for high-quality photomask supply. These incentives are not distributed evenly across the value chain; they favor regions and technologies aligned with national security and advanced manufacturing priorities.
Beyond policy, operational realities are testing manufacturers. Supply chain constraints on high-purity quartz substrates and specialty materials were reported by 27 percent of manufacturers, introducing variability in lead times and cost predictability. Such constraints are not merely tactical inconveniences; they influence capacity planning, vendor selection, and the geographic distribution of production assets. Our report maps these dynamics in granular detail, offering a framework for assessing regulatory exposure, material dependency, and the strategic value of nearshoring or dual-sourcing arrangements.
Photomask Market
Competitive Architecture: Leaders, Moves, and Market Concentration
The photomask industry is characterized by a concentrated yet dynamic competitive structure. Our analysis indicates that the top three players collectively command approximately 45 percent of global revenue, while the top five entities account for roughly 60 percent. This concentration reflects the high barriers to entry associated with advanced lithography mask fabrication, stringent quality requirements, and the capital intensity of maintaining cutting-edge process capabilities. Yet within this consolidated landscape, strategic moves, geographic expansions, and technological investments are continuously reshaping the competitive equilibrium.
Among the most prominent players, Photronics Inc., headquartered in Brookfield, Connecticut, operates as a merchant leader providing integrated circuit and flat-panel display photomasks across eleven global facilities spanning North America, Asia, and Europe. In May 2026, the company reported second-quarter fiscal 2026 results that highlighted ongoing investments in U.S. and Korean facilities aimed at expanding advanced photomask capacity. This dual-region strategy underscores a broader industry trend: balancing proximity to leading-edge logic and memory clusters with the operational resilience offered by geographically distributed manufacturing footprints.
In Japan, Tekscend Photomask Corp.—rebranded from Toppan Photomask and based in Tokyo—has emerged as a global provider of semiconductor photomasks and related microfabrication products, maintaining facilities across Japan, the United States, Europe, and Asia. Tekscend's recent activity illustrates an aggressive capacity expansion posture. In October 2025, the company held a groundbreaking ceremony for a new photomask manufacturing facility in Singapore, designed to supply advanced precision photomasks to high-growth nodes. Just months later, in January 2026, Tekscend received a $15.2 million grant from the Texas government to expand its Round Rock facility by over 40 percent and create 50 new jobs. These parallel investments signal a deliberate strategy to position capacity closer to both North American and Asia-Pacific demand centers while capitalizing on regional incentive structures.
Dai Nippon Printing Co., Ltd., also headquartered in Tokyo, has focused its innovation pipeline on photomasks for advanced extreme ultraviolet (EUV) lithography nodes, including 3nm and 2nm process technologies. As EUV continues to define the frontier of logic scaling, suppliers capable of delivering masks with the requisite pattern fidelity, defect control, and material performance gain strategic leverage in the value chain. Hoya Corporation, another Tokyo-based leader, dominates the supply of EUV mask blanks and photomask blanks, occupying a critical upstream position that influences the entire mask fabrication ecosystem. Broadly, Hoya's position reflects the reality that blank quality and availability are gating factors for downstream mask makers, linking material science directly to lithography yield.
Rounding out the competitive set, SK-Electronics Co., Ltd., based in Seongnam, South Korea, stands as a major supplier of semiconductor photomasks and mask blanks, reinforcing the importance of Korean manufacturing ecosystems in the global photomask supply chain. Collectively, these players demonstrate that competitive advantage in this market is not simply a function of scale; it is increasingly defined by technological readiness for next-generation nodes, geographic alignment with fab expansion, and the ability to navigate regulatory and material constraints without compromising delivery.
What the Full Report Delivers: Operational Intelligence for 2026 Decision-Making
Our Semiconductor Photomask Market research is structured to move beyond high-level market sizing and into the operational and strategic details that decision-makers require. The report integrates historical performance data, forward-looking forecasts, and a multi-dimensional segmentation framework that allows readers to isolate growth drivers, assess risk exposures, and benchmark competitive positioning. Below is a preview of the core components embedded in the full analysis.
Segmentation by Region: Geographic Demand and Incentive Landscapes
The regional breakdown of market activity provides essential context for capacity siting, sourcing strategies, and competitive targeting. Northern America represents the largest revenue concentration, followed by Asia Pacific, which captures the second-largest share of global activity. Europe, Latin America, and the Middle East and Africa collectively account for the remaining portion, with distinct growth profiles and policy environments. Rather than presenting static percentage allocations, the report examines how regional demand patterns intersect with fab investment cycles, incentive programs such as the CHIPS Act, and the geographic placement of mask fabrication and blank supply assets. This lens helps strategists identify where demand is likely to outpace local supply and where partnership or capacity expansion opportunities may emerge.
Segmentation by Type: Reticle, Master, and Supporting Products
The product mix dimension is central to understanding vendor economics and technology roadmaps. Reticle-type photomasks command the highest revenue share, reflecting their critical role in high-volume manufacturing of integrated circuits. Master masks and other product categories contribute meaningful revenue streams, often serving specialized applications or acting as enabling inputs for next-generation processes. The report analyzes how the relative weight of each product category is evolving as node scaling, multi-patterning requirements, and display manufacturing demands shift the demand mix. This analysis is particularly valuable for suppliers evaluating portfolio prioritization and for buyers assessing long-term supply reliability across mask types.
Segmentation by Application: End-Market Demand Drivers
Demand for photomasks is ultimately anchored in the end markets they enable. Display manufacturing represents the largest application vertical, driven by the ongoing transition to high-resolution panels and advanced organic light-emitting diode technologies. Discrete components and optical devices form the next tier of demand, each with distinct technology roadmaps and procurement cycles. Microelectromechanical systems, while smaller in aggregate revenue, represent a high-precision segment where mask quality directly affects device performance. The full report examines how these application segments are expected to grow over the forecast period, what differentiates their pricing and specification dynamics, and how shifts in consumer electronics, automotive, and industrial demand translate into photomask order books.
Competitive Profiling and Tactical Intelligence
Beyond company-level profiles, the report synthesizes recent developments, facility investments, and strategic announcements to build a living map of competitive intent. Coverage includes expansion grants, new facility groundbreakings, equipment installation milestones, and financial reporting highlights that reveal where leading players are allocating capital. For example, the report contextualizes Tekscend Photomask's dual expansion in Texas and Singapore alongside Photronics' investments in U.S. and Korean facilities, using these moves to illuminate broader themes such as regional incentive capture, capacity localization, and node-specific capability building. This competitive intelligence is designed to support supplier selection, partnership evaluation, and strategic positioning exercises.
Translating Intelligence into 2026 Action Plans
Market research delivers value only when it is operationalized. Our report is built with that principle in mind, offering analytical structures that can be integrated directly into corporate strategy workflows. For capacity planners and procurement leaders, the segmentation frameworks provide a basis for demand forecasting, supplier diversification, and lead-time risk management—particularly important given the reported material constraints and the evolving regulatory environment. For investors and corporate development teams, the competitive profiling and growth trajectory analysis offer a foundation for evaluating market entry feasibility, partnership structures, and the strategic implications of concentration dynamics.
For executives monitoring geopolitical risk, the report's integration of policy actions—from tariff impositions and Section 232 investigations to export control discussions and incentive program impacts—creates a scenario-ready view of how regulatory shifts could affect cost structures, sourcing options, and regional competitiveness. This is not a static snapshot; it is a structured assessment that can be calibrated as policy trajectories and material supply conditions evolve.
Why the Full Intelligence Package Matters
The preview provided here captures the analytical architecture and strategic relevance of our Semiconductor Photomask Market research, but the complete report contains the detailed segmentation data, company-level profiling, scenario analysis, and forward-looking forecasts that enable precise decision-making. The macro numbers—$4,010 million in 2025, a 5.8 percent CAGR, and a projected $5,919 million market size by 2032—set the stage. The real strategic advantage lies in understanding where growth concentrates, how competitive moves reshape supply dynamics, and which regulatory and material risks demand proactive mitigation.
Semiconductor Photomask Market
To access the complete segmentation breakdowns, in-depth company profiles, regulatory impact assessments, and forecast models that power these insights, we invite you to explore the full research on our website. The report is designed for leaders who need more than a market overview—they need a decision-grade intelligence framework aligned with the realities of 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Semiconductor Photomask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pad Printing Supplies Market to Hit $267.3M by 2032 with 5.65% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Pad Printing Supplies Market: A 2032 Outlook
For procurement leaders, R&D directors, and competitive intelligence teams operating in industrial decoration and precision marking, the Pad Printing Supplies Market represents a microcosm of broader manufacturing shifts.
Over the past half-decade, the industry has navigated raw material volatility, tightening chemical regulations, and accelerating demand for eco-compliant consumables. The newly released Pad Printing Supplies Market research report distills these dynamics into a decision-grade framework, offering enterprise stakeholders a clear line of sight from historical performance through 2032. This overview previews the analytical architecture of the study and explains why its insights are indispensable for 2026 strategy formation.
The report is built on a rigorous methodological foundation that tracks revenue movement from 2020 through the base year of 2025. Historical data captures the market at roughly US$148.75 million in 2020, progressing through a series of incremental expansions to reach US$182.0 million by 2025. This trajectory reflects the sector's resilience against supply chain disruptions and its steady adoption in high-mix, low-volume production environments. Looking ahead, the forecast horizon extends to 2032, projecting the total market to surpass US$267 million over the period. The implied compound annual growth rate of 5.65 percent provides a reliable benchmark for investment pacing, capacity planning, and product roadmapping. Rather than presenting isolated figures, the study embeds these numbers within demand-side drivers, regulatory headwinds, and regional supply chain reconfigurations.
A defining feature of the 2026–2032 outlook is the tension between end-use momentum and material compliance. Pad printing has long been favored for its ability to reproduce fine detail on irregularly shaped substrates, but recent years have elevated the stakes for ink chemistry, pad durability, and cliché precision. Manufacturers serving consumer goods, hard goods, and identification applications increasingly require consumables that satisfy a mosaic of regulatory frameworks without sacrificing adhesion or line quality. The research report maps how these requirements reshape procurement criteria, how suppliers are re-engineering solvent and UV-based chemistries, and where end-users are willing to pay a premium for certified, low-VOC, and phthalate-free formulations. By examining the intersection of technical performance and compliance cost, the study provides a practical lens for evaluating total cost of ownership rather than sticker price alone.
Decoding the Market Structure: Concentration, Type, and Application Pressures
Market structure analysis is central to any credible strategic assessment, and this report approaches the Pad Printing Supplies Market with particular attention to competitive density and segmentation behavior. The sector exhibits moderate concentration at the top tier, with the leading three players accounting for approximately 32.4 percent of aggregate revenue and the top five reaching roughly 47.6 percent. Such figures signal a landscape where scale, distribution footprint, and technical service capabilities provide durable advantages, yet where specialized regional players and product-focused specialists retain meaningful share through customization and rapid turnaround.
Within this framework, the analysis examines how supply portfolios split across ink technologies and auxiliary materials. Solvent-based chemistries continue to hold a prominent position, reflecting entrenched manufacturing workflows and cost-performance expectations in established production lines. At the same time, UV-curable systems are steadily gaining relevance as throughput requirements intensify and cure-on-demand workflows reduce energy and solvent management burdens in controlled factory environments. Ceramic formulations and other specialized ink categories occupy a smaller but strategically significant role, particularly where marking durability, thermal exposure, and surface compatibility are decisive. The report evaluates how these type-level dynamics influence supplier negotiations, inventory strategies, and substitution risks across different production contexts.
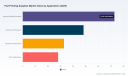
On the application side, the research dissects the demand architecture across major end-use categories. Glass and plastic products represent a substantial portion of the addressable market, consistent with the versatility of pad printing on non-flat surfaces and the enduring need for labeling, logo replication, and identification across consumer and industrial goods. Ceramic and porcelain applications form another significant pillar, driven by tableware, sanitaryware, and decorative goods manufacturers that demand inks capable of bonding to glazed and unglazed surfaces under varied curing conditions. Electronic components constitute an increasingly important niche, where miniature print fidelity, material compatibility, and traceability requirements push suppliers toward tighter process control and more specialized consumables. A broader set of remaining applications rounds out the demand matrix, illustrating how pad printing continues to migrate into adjacent use cases. The study deliberately avoids one-dimensional allocation tables, instead framing each application segment through operational requirements, regulatory exposure, and growth sensitivity to macroeconomic demand cycles.
Regional Divergence and Supply Chain Realities
Geographic context is indispensable for understanding where growth is being generated and how supply chains are adapting. The report profiles the Pad Printing Supplies Market across five major regional clusters: North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents a distinct combination of manufacturing density, regulatory posture, distributor infrastructure, and end-user purchasing behavior.
North America reflects a mature demand environment supported by a broad base of industrial decorators, packaging specialists, and contract manufacturers who prioritize reliability, service responsiveness, and compliance documentation. European operations are shaped by stringent chemical legislation, high labor costs, and an industry that increasingly rewards sustainable formulators and suppliers with traceable quality systems. Asia Pacific combines the most expansive manufacturing backdrop with rapidly evolving automation adoption, making it a region where volume, localization, and price competitiveness intersect with rising quality expectations. Latin America and the Mideast and Africa represent smaller yet strategically relevant markets, where import dependency, freight variability, and selective industrial growth patterns influence both supplier entry decisions and procurement timing.
Pad Printing Supplies Market
Worldwide Specialty Ink Market
Rather than reducing these dynamics to static share figures, the study assesses how regional differences alter lead-time risk, inventory buffering, formulation requirements, and aftermarket service expectations. The result is a practical decision tool for companies evaluating distribution expansion, localized stocking, or cross-border sourcing adjustments as the forecast period unfolds.
Competitive Landscape: Eight Companies Setting Different Standards
No market assessment is complete without a grounded view of the competitors actually shaping supply. The Pad Printing Supplies Market is populated by firms that compete on different axes: comprehensive consumables portfolios, machine and tooling integration, eco-certification leadership, and regional distribution scale. The research report profiles eight companies that exemplify these strategic postures and influence buying expectations across multiple segments.
TAMPOPRINT AG, headquartered in Germany, structures its offering around a complete pad printing consumables line, including inks, clichés, printing pads, ink and doctoring cups, auxiliary materials, and laser cliché production. This breadth positions the company as a one-stop resource for operations that prefer consolidated specification and reduced vendor fragmentation. INX International, based in the United States, emphasizes performance and regulatory alignment through its INXPad T200 solvent-based and UV pad printing inks. Its eco-formulations are designed to be free from phthalates and BPA, targeting packaging and product decoration environments where compliance documentation carries commercial weight. Marabu Druckfarben, also German, maintains a wide range of solvent-based and UV-curable pad printing inks focused on industrial decoration, marking, and identification, appealing to users with high repeatability requirements across varied substrate types.
Teca-Print USA, operating from the United States, concentrates on consumables supported by custom-mixed inks, printing pads, cliché plates, and full automation support, making it relevant for shops moving from manual to semi-automated workflows. Inkcups Now Corporation, likewise U.S.-based, has built visibility around ink cups, ceramic rings, and eco-responsible ink systems, including its SB Eco Series certified under GOTS and compliant with REACH and RoHS. Printex USA rounds out the equipment-plus-consumables profile by offering custom pad printing machines, tooling, fixtures, and consumables tailored for high-volume automated applications. ITW Trans Tech provides a full range of pad printing machines, fixtures, inks, pads, and printing plates, reinforced by what is described as the largest North American ink warehouse, a structural advantage for customers sensitive to replenishment speed. Boston Industrial Solutions differentiates through in-house silicone pads, inks, plates, fixtures, and accessories, allowing tighter control over the physical interface between pad, ink film, and substrate.
Regulatory Change as a Demand-Shaping Force
Regulatory and certification developments are no longer peripheral concerns in this market; they actively redirect procurement decisions and product roadmaps. A March 2025 milestone underscores this shift, when seven inks in the SB Eco Series achieved GOTS certification, reinforcing the broader movement toward formulations free from naphtha, PAH, and cyclohexanone while satisfying REACH, RoHS, and EN 71-3. This trajectory matters because it alters the qualification threshold for suppliers serving consumer-facing and regulated product categories.
A September 2025 product launch further illustrates how performance and compliance are being engineered together. The introduction of INXPad T200 solvent-based pad printing inks at K 2025 highlighted a sustainable system intended to enable recycling of recovered packaging materials while delivering high durability for toys, electronics, automotive, and promotional items. Equally important, these inks are described as free from phthalates and BPA and suitable for printing onto the non-food contact side of packaging, with compliance spanning REACH, RoHS, the Swiss Ordinance, the Toy Safety Directive, the GADSL list, and the EuPIA Exclusion Policy. Marabu has similarly aligned its pad printing inks with REACH and RoHS requirements, while broader industry references point to ISO 9001 and ISO 14001 certified ink lines with medical-grade biocompatibility testing, as well as eco-certified consumables validated under Eco-Passport, CLP/GHS, EN 71-3, REACH, and RoHS. These developments are not isolated; they signal that chemical stewardship, traceability, and certification readiness are increasingly part of the baseline commercial evaluation.
Inside the Research: What Decision-Makers Can Use Immediately
The strategic value of this report lies in its operational specificity. It is designed not only to explain market direction but to support concrete choices in sourcing, forecasting, and competitive positioning. Readers can expect a structured analysis that moves from macro trajectory to actionable segmentation intelligence, while preserving the analytical discipline needed to avoid overgeneralizing across diverse end-use contexts.
Key components include:
- A historical-to-forecast revenue assessment that benchmarks the current cycle and clarifies the pace of expansion through 2032.
- Systematic coverage of type-level dynamics across solvent-based, UV-curable, ceramic, and other ink portfolios, framed by performance trade-offs and regulatory exposure.
- Application-level evaluation across glass and plastic products, ceramic and porcelain, electronic components, and other use cases, emphasizing operational requirements and demand sensitivity.
- Regional analysis that links localized manufacturing conditions, distribution logistics, and compliance expectations to procurement strategy.
- Competitive profiling of major suppliers with attention to product breadth, automation support, eco-certification, and service infrastructure.
- Structured tracking of recent developments, certifications, and regulatory alignments that are reshaping qualification criteria for consumables.
- Decision-oriented synthesis for capacity planning, vendor consolidation, formulation selection, and market-entry prioritization.
By balancing breadth with depth, the study avoids the common pitfall of presenting segmentation data in isolation. Instead, it connects type, application, and regional behavior to real procurement pressures, allowing users to interpret numbers within the operational context that actually drives purchasing decisions.
Why 2026 Demands a Sharper Market View
The 2026 decision environment will be defined by a combination of demand stability, formulation evolution, and compliance-driven qualification. With the total market projected to reach approximately US$198.38 million in 2026 and continue expanding toward US$267.3 million by 2032, the size of the opportunity is clear. The more difficult question for enterprise teams is where growth will accrue, which product categories will face substitution pressure, and how quickly regulatory expectations will alter approved-supplier lists. A 5.65 percent CAGR is not merely a headline statistic; it is a planning parameter that helps set expectations for revenue expansion, inventory investment, and R&D prioritization across the forecast window.
At the same time, market concentration around the top three and top five players indicates that scale and service reliability still matter. Enterprises that depend on just-in-time replenishment, tight color matching, or specialized pad and cliché performance will need to assess not only what suppliers offer today but how those suppliers are adapting to sustainability, documentation, and automation demands. The report's competitive and regulatory analysis is intended to support those evaluations with current evidence rather than assumptions.
From Insight to Action: Accessing the Full Intelligence
Pad printing may be a specialized process, but its consumables market reflects the same strategic truth facing most industrial supply sectors: performance, compliance, and supply continuity now intersect in ways that reward early, evidence-based positioning. The Pad Printing Supplies Market research report is designed to give executives, procurement teams, and market strategists that evidentiary base. It consolidates historical trajectory, forward-looking growth modeling, competitive profiling, and regulatory developments into a single analytical structure tailored to practical use.
To move from directional understanding to fully segmented, decision-grade intelligence, the complete dataset and detailed analytical breakdown are available through the published report. The full market size progression, segmentation coverage, regional interpretation, and company-level assessments provide the granularity needed for budgeting, sourcing strategy, and competitive response planning. For teams preparing 2026 initiatives, the report offers both the context to interpret market movement and the structured evidence to act on it with confidence.
For detailed analysis of this topic, please visit the official page: Pad Printing Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gel Batteries Market Hits $2.49B in 2025, Poised for 7.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in Gel Batteries: Navigating Growth Through 2032
The global energy storage landscape is undergoing a profound transformation, driven by the urgent need for reliable, safe, and cost-effective backup solutions. Within this shifting paradigm, the Gel Batteries Market stands out as a critical segment, offering distinct advantages in deep-cycle endurance and maintenance-free operation. As we move beyond 2025, understanding the trajectory of this market is not merely an academic exercise but a strategic necessity for stakeholders across telecommunications, renewable energy, and industrial sectors. PW Consulting's latest market research provides a comprehensive roadmap for navigating this complex environment, equipping decision-makers with the intelligence required to capitalize on emerging opportunities through 2032.
A Decade of Growth: Macro Trends and Financial Trajectories
The historical performance of the gel battery sector underscores its resilience and expanding relevance. From a baseline of 1.0 billion USD in 2020, the market has demonstrated consistent upward momentum, reaching 2.49 billion USD by 2025. This growth reflects a broader industrial shift toward valve-regulated lead-acid (VRLA) technologies that mitigate the risks associated with liquid electrolytes, such as leakage and corrosion. The stability of this expansion is projected to continue, with revenues anticipated to climb to 2.7 billion USD in 2026 before accelerating toward 4.04 billion USD by 2032.
Gel Batteries Market
This trajectory is underpinned by a compound annual growth rate (CAGR) of 7.2 percent during the forecast period of 2026 to 2032. For strategic planners, this figure is more than a statistic; it represents a robust avenue for capital allocation and product development. The sustained growth indicates that gel technology is not being rendered obsolete by newer chemistries but is instead finding specialized niches where reliability outweighs the premium cost sometimes associated with lithium alternatives. Our report delves into the drivers sustaining this CAGR, analyzing how regulatory pressures and infrastructure upgrades contribute to steady demand across key verticals.
Segmentation Dynamics: Type and Application Insights
Understanding where value is generated within the market is crucial for targeted strategy. The market is primarily divided by type into stationary and motive power segments. The stationary segment larger share in 2025, driven by the relentless rollout of telecommunications infrastructure and renewable energy storage systems. Telecom operators rely heavily on gel batteries for base station backup due to their tolerance for varying temperatures and extended shelf life. Similarly, the renewable energy sector utilizes gel batteries to stabilize output from solar and wind installations, ensuring power availability during intermittent generation periods.
The application landscape further nuances this demand. Telecommunications and renewable energy storage represent significant pillars of consumption, absorbing substantial portions of production capacity. However, the others category remains a diverse and vital component, encompassing industrial machinery and specialized marine applications. Our analysis dissects these segments to identify which sub-verticals are experiencing the fastest adoption rates. While specific regional percentages are reserved for the full report to protect client confidentiality and encourage deeper engagement, the qualitative trend is clear: stationary applications are the primary engine of growth, supported by grid modernization efforts globally.
Regional Perspectives and Demand Hotspots
Geographically, the market exhibits varied maturity levels and growth potentials. Asia Pacific represents a significant volume driver, fueled by rapid industrialization and substantial investments in grid storage capabilities. North America and Europe continue to be mature markets where replacement cycles and sustainability regulations drive steady demand. Meanwhile, emerging regions in Latin America and the Middle East and Africa offer nascent but high-potential opportunities as infrastructure development accelerates.
Our research provides a granular view of these regional dynamics without limiting the scope to static market shares. Instead, we focus on the underlying economic and policy factors influencing regional adoption. For instance, government policy reports from 2025 indicate that carbon tax policies and emission reduction goals are driving industry-wide adoption of VRLA gel technology in multiple regions. This regulatory tailwind is particularly potent in Europe and parts of Asia, where compliance costs for less efficient technologies are rising. Understanding these regional policy landscapes is essential for companies planning supply chain logistics and market entry strategies.
Competitive Landscape: Key Players and Strategic Moves
The market concentration is moderate, with the top three companies holding approximately 48 percent of the market share and the top five controlling around 62 percent. This structure suggests a competitive environment where established giants coexist with specialized manufacturers capable of innovating quickly. Several key companies define the current landscape, each leveraging unique technological strengths.
Exide Technologies, headquartered in India, has long been a cornerstone of the market. Their focus on patented gel dryfit VRLA technology positions them strongly for deep-cycle applications including marine, equipment, and renewable energy storage. In February 2025, Exide Technologies announced a 100 million USD investment to expand gel battery manufacturing capacity, a direct response to demand surges from renewable energy and telecom sectors. This capital expenditure signals a strong commitment to capturing the forecasted growth in the 2026 to 2032 period.
Trojan Battery Company, based in the United States, maintains a strong foothold with deep-cycle gel batteries tailored for solar, marine, and off-grid renewable energy systems. Their product philosophy emphasizes longevity and reliability in remote settings, aligning with the needs of the expanding microgrid market. Similarly, East Penn Manufacturing offers the Deka Ready Power gel battery line, catering to both motive power and renewable applications, ensuring versatility across industrial and energy storage use cases.
In the industrial and telecom spheres, GS Yuasa Corporation of Japan provides gel lead-acid batteries optimized for industrial, renewable, and telecom energy storage. Their reputation for quality in extreme conditions makes them a preferred partner for critical infrastructure. Amara Raja Batteries, also based in India, contributes significantly with gel batteries for industrial and renewable energy storage solutions, leveraging local manufacturing capabilities to serve regional demand efficiently.
European influence remains strong through entities like Sonnenschein Batteries, which operates under the Exide Group umbrella. In January 2025, Sonnenschein Batteries unveiled a new high-capacity gel battery specifically for grid storage and renewable integration projects. This product launch highlights the industry trend toward higher capacity units capable of supporting utility-scale applications. Further west, Banner Batteries from Austria continues to supply gel batteries for industrial and renewable energy uses, maintaining high standards for European market compliance. Enersys, another United States-based player, focuses on gel battery technology for motive and stationary energy storage applications, bridging the gap between material handling equipment and fixed storage solutions.
Recent Developments and Innovation Trajectories
Innovation within the sector is not limited to established names. Recent developments indicate a broadening of technical capabilities. In February 2025, Narada Power opened a new R&D center in Shanghai dedicated to next-generation gel battery chemistry and manufacturing processes. This move underscores the importance of Asian R&D hubs in advancing global technology standards. Furthermore, in March 2025, Hoppecke Batteries launched a modular gel battery system for commercial EV fleets offering enhanced safety and lifecycle performance. This development illustrates the convergence of gel battery technology with electrification trends in transportation, expanding the potential addressable market beyond traditional stationary uses.
Regulatory Frameworks and Industry Dynamics
Navigating the regulatory environment is as critical as managing technology roadmaps. Battery Council International convened the first-ever meeting of its Sodium Battery Industry Group on May 4 2026 to advance standards for energy storage technologies including advanced lead-acid variants. While focused on sodium, this regulatory push signals a broader scrutiny and standardization effort across energy storage chemistries, which indirectly benefits established gel technologies by clarifying compliance pathways.
Sector Analysis indicates targeted renewable energy subsidies and grid code updates continue to support deployment of gel battery systems in utility-scale storage applications. These financial incentives lower the barrier to entry for large-scale projects, making gel batteries a financially viable option for utility planners. However, compliance is mandatory. ISO 9001 and ISO 14001 certifications are mandated for all gel battery production facilities to ensure quality and environmental compliance. Manufacturers failing to meet these standards face exclusion from supply chains in regulated markets.
Supply chain stability also hinges on critical mineral management. Lead remains the core critical mineral in gel batteries with ongoing mining and recycling efforts by major producers supporting supply chain stability. Investors and procurement officers must monitor these supply dynamics closely, as fluctuations in lead availability can impact production costs and margins. Our report evaluates these supply chain risks in detail, offering strategies for mitigating material volatility.
Tubular GEL Battery Market
Strategic Value of the PW Consulting Report
For executives and strategists, accessing detailed market intelligence is the first step toward informed decision-making. This report goes beyond surface-level data to provide actionable insights. It examines the intersection of policy, technology, and demand to forecast how the market will evolve. Readers will gain clarity on which applications are poised for expansion and where competitive intensity might compress margins.
The analysis of market concentration helps identify consolidation opportunities. With the top five players controlling over 60 percent of the market, there is a clear hierarchy. However, the presence of agile R&D centers and new product launches suggests that niche players can carve out profitable segments. Understanding where these opportunities lie requires the depth of analysis provided in our full study. We explore how companies like Exide and Trojan are adjusting their portfolios to meet the demands of 2026 and beyond, offering case studies on successful capacity expansions and product innovations.
Furthermore, the report addresses the risks associated with regulatory changes. As ISO mandates tighten and carbon policies evolve, manufacturers must adapt their processes. Our findings outline the compliance requirements necessary to maintain market access. For investors, this due diligence is invaluable in assessing the viability of potential partners or acquisition targets.
Conclusion: Positioning for the 2032 Horizon
The Gel Batteries Market is on a steady path of expansion, driven by the inherent advantages of the technology and supportive macroeconomic trends. The projected growth from 2.7 billion USD in 2026 to over 4 billion USD by 2032 offers substantial room for strategic maneuvering. However, realizing value in this market requires more than optimism; it demands precise intelligence on segmentation, competition, and regulatory shifts.
PW Consulting's comprehensive market research serves as an essential tool for navigating this landscape. By synthesizing historical data, forecasting future trends, and analyzing the moves of key competitors, we provide a foundation for robust strategic planning. Whether you are looking to invest in manufacturing capacity, enter new geographic regions, or develop next-generation storage solutions, the insights contained in this report are designed to guide your approach. The full depth of segmentation data, regional breakdowns, and competitive profiling is available through our complete study, ensuring you have the specific intelligence needed to lead in this evolving sector.
For detailed analysis of this topic, please visit the official page: Gel Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Forging Presses Market Hits USD 208.45M in 2025, Poised for 4.3% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Forging Presses Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a profound transformation, driven by the dual imperatives of industrial decarbonization and the relentless demand for high-strength, precision-engineered components. At the heart of this evolution lies the forging presses market, a critical machinery segment that underpins automotive lightweighting, aerospace structural integrity, and heavy industrial capacity. As we move into 2026, enterprise leaders and capital equipment strategists require more than fragmented data points. They need a cohesive, forward-looking intelligence framework that maps market trajectories, competitive maneuvering, and technological inflection points. Our newly released Forging Presses Market research report delivers precisely that: a comprehensive, decision-ready blueprint designed to align capital allocation, R&D prioritization, and Supply Chain positioning with the realities of the coming decade.
Market Architecture and the 2026 Growth Trajectory
Understanding the forging presses market requires a clear view of its structural evolution over the past half-decade. The sector has demonstrated consistent expansion, with total market revenue climbing steadily from 2020 through 2025 as global industrialization, infrastructure investment, and advanced manufacturing adoption compounded demand. This historical momentum has established a robust foundation for the current forecast window, which extends through 2032. The baseline year of 2025 reflects a mature yet dynamically expanding market, and the trajectory projected for 2026 indicates a meaningful inflection in capital equipment orders, technological upgrades, and regional capacity realignment.
Forging Presses Market
Our analysis projects a compound annual growth rate of 4.3 percent across the forecast horizon. While this figure may appear moderate at first glance, it obscures a far more important narrative: growth is not uniformly distributed. It is concentrated in specific technology pathways, application verticals, and geographic corridors where regulatory pressure, energy economics, and labor constraints are simultaneously reshaping procurement behavior. The 2026 market milestone represents more than a numerical checkpoint. It signals a transition phase where legacy mechanical systems are being strategically supplemented or replaced by hydraulic and servo-driven platforms that offer precision, energy recovery, and automation compatibility. For executives evaluating capacity expansion, modernization cycles, or cross-border equipment sourcing, understanding the timing and sequencing of this transition is essential. The research unpacks the underlying drivers of this growth curve, mapping how macroeconomic indicators, raw Material cost structures, and plant-level efficiency mandates converge to influence purchasing decisions at the operational level.
Segmentation Dynamics: Where Value Is Being Created
A superficial reading of market size inevitably leads to misallocated resources. The Forging Presses Market is characterized by distinct segmentation layers, each with its own technology adoption cycles, end-user procurement logic, and competitive intensity. Mechanical forging systems continue to hold substantial share, particularly in high-volume production environments where throughput consistency and established maintenance ecosystems remain advantageous. Yet the hydraulic segment is capturing disproportionate attention from capital manufacturers and end-user engineering teams. This shift is not merely a preference for newer technology. It reflects a structural realignment toward applications demanding complex part geometries, variable tonnage control, and integration with downstream automated handling systems.
Application-side dynamics further illustrate where strategic focus is accumulating. Automotive manufacturing remains a primary demand engine, driven by the ongoing transition toward lighter structural components, electrification-compatible housing designs, and closed-die precision requirements. Aerospace demand sustains a parallel growth vector, with stringent material certification standards and fatigue-critical component specifications pushing forging specifications toward higher tonnage capabilities and tighter tolerance tolerances. Beyond these dominant verticals, hardware tools, general machinery, and specialized industrial applications contribute to a diversified demand base that buffers the market against cyclical downturns in any single sector. Regional demand patterns similarly reveal nuanced deployment strategies, with established industrial corridors sustaining steady replacement and upgrade cycles while emerging manufacturing hubs accelerate new capacity installations. Our report dissects these segmentation layers without reducing them to isolated percentages, instead presenting them as interacting forces that dictate pricing power, lead-time expectations, and technology roadmapping for equipment suppliers and buyers alike.
Competitive Landscape and Strategic Positioning
The forging presses market is defined by a concentrated yet highly differentiated competitive field. Leading manufacturers are no longer competing solely on tonnage ratings or unit pricing. They are competing on system integration, energy performance, automation readiness, and aftermarket service ecosystems. Our competitive analysis maps the strategic profiles of the sector's most influential players, tracing how each organization is positioning itself across mechanical, hydraulic, and hybrid technology pathways.
Cold Forging Machine Market
North American manufacturers maintain a strong footprint by emphasizing custom engineering, application-specific configurations, and responsive service networks. Companies such as Beckwood Press Company and Ajax-Ceco Machinery have built enduring reputations around hydraulic solutions tailored to both open-die and closed-die operations, with capacity ranges that address mid-to-large industrial requirements. Verson, operating within the broader SMS Group portfolio, provides a diversified offering spanning mechanical, hydraulic, and servo configurations, enabling end-users to align press specifications with variable production targets. Stamtec and C.W. Bear Company reinforce the segment's breadth by supplying mechanical, cold, and warm-hot forging solutions alongside supporting metal forming equipment. Distributors and component specialists such as L.T. Rogers Company and C.E. Johns & Co. play essential roles in sustaining ecosystem resilience, ensuring that legacy installations can be upgraded, maintained, and retrofitted as technology standards advance. National Forging Company and The Precision Hydraulic Press Co. further illustrate the market's dual identity as both an equipment manufacturing space and an operational service environment, while Hydro Punch Press Inc. and Sintokogio America Inc. address specialized forming and heavy industrial requirements. Jier Machine Tool and Macrodyne round out the competitive field with large-capacity hydraulic and servo solutions, the latter extending its reach into ultra-high-tonnage applications that serve extreme industrial demands.
International players are equally reshaping market expectations. Schuler Group has emerged as a global reference point for hydraulic and hybrid press architectures, leveraging advanced energy recovery systems and precision control frameworks to meet stringent European and global efficiency benchmarks. AIDA Engineering and Komatsu Industries contribute high-volume mechanical and servo capabilities that align with disciplined production cadence requirements, while SMS Group continues to expand its automation-integrated hydraulic press offerings for both open-die and closed-die environments. Fagor Arrasate reinforces the European supply base with forming machine expertise that complements broader press ecosystems. The result is a competitive landscape where differentiation is increasingly measured by engineering flexibility, environmental compliance, and lifecycle economics rather than hardware specifications alone.
Innovation Vectors and Recent Developments
Technology momentum in the forging presses market is accelerating, and recent developments provide a clear window into the direction of industry evolution. In July 2025, Maxiforja Group initiated production on the world's largest forging press delivered by ANDRITZ Schuler, incorporating a Kinetic Energy Recovering System that exemplifies the sector's move toward energy-conscious heavy manufacturing. Shortly thereafter, in October 2025, Schuler AG completed the delivery of its first full hybrid hydraulic-electric 4000-ton press to Audi Neckarsulm, achieving a 28 percent reduction in energy consumption. These milestones are not isolated engineering accomplishments. They demonstrate a broader industry pivot where energy recovery, hybrid actuation, and digital control integration are becoming procurement prerequisites rather than optional enhancements.
Also in October 2025, SMS Group successfully commissioned a fully automatic closed-die forging press at TZCO Chain Manufacturing in China, achieving throughput rates of up to 30 strokes per minute. This deployment underscores the growing importance of automation integration in high-cadence production environments, where labor constraints and consistency requirements are pushing manufacturers toward fully automated press lines. More recently, in May 2026, Macrodyne participated in the Forging Industry Technical Conference, signaling continued engagement with end-users, engineering teams, and technology partners around next-generation hydraulic and servo press architectures. These developments collectively illustrate an industry that is simultaneously scaling capacity and compressing energy intensity, a duality that directly informs equipment selection criteria and capital planning timelines.
Structural Forces Reshaping Procurement and Investment
Beyond corporate announcements and tonnage milestones, several structural forces are redefining how forging presses are specified, purchased, and operated. Carbon steel continues to account for a significant share of raw material utilization within the forging sector, driven by its favorable balance of cost-effectiveness and mechanical strength. This material dependency influences not only component design but also press tonnage selection, die durability expectations, and maintenance scheduling. Equipment strategies that ignore material-specific forming behavior risk suboptimal lifecycle economics and increased downtime.
Regulatory and energy efficiency mandates are exerting equally powerful pressure. Industry guidance now expects forging press technologies to deliver energy consumption reductions in the range of 22 to 35 percent compared to conventional systems. This benchmark is reshaping vendor evaluation frameworks, as procurement teams increasingly factor operational energy costs, recovery capabilities, and control system efficiency into total cost of ownership calculations. Simultaneously, persistent labor shortages across forging operations are accelerating investment in automation, digital control systems, and semi-autonomous press lines. Plant operators are no longer treating automation as a future-state aspiration. They are implementing it as a near-term operational necessity to mitigate personnel constraints, stabilize production cadence, and reduce variability in part quality. These dynamics converge to create a market environment where equipment decisions must account for energy performance, labor economics, and material behavior in an integrated manner. Our report provides the analytical scaffolding required to evaluate these forces systematically, allowing decision-makers to anticipate procurement timing, technology adoption windows, and competitive response patterns.
What This Research Delivers for 2026 Decision-Making
The Forging Presses Market research is structured to translate complex market data into actionable strategic guidance. Rather than presenting static tables in isolation, the report integrates market sizing, segmentation logic, competitive profiling, and macro-industrial context into a unified decision framework. Readers will find detailed assessments of mechanical and hydraulic technology pathways, including adoption drivers, performance trade-offs, and lifecycle cost implications. The application-side analysis connects end-user requirements in automotive, aerospace, hardware tools, general machinery, and other industrial sectors to specific press configurations and procurement behavior. Regional market dynamics are examined through the lens of capacity deployment, demand maturity, and technology diffusion patterns, providing context for sourcing strategies and market-entry considerations.
The competitive analysis extends beyond company summaries to evaluate strategic positioning, technology emphasis, and ecosystem influence. Recent developments are contextualized within broader industry trends, enabling readers to distinguish between discrete events and structural shifts. Market concentration metrics are incorporated to illuminate the balance between established incumbents and specialized challengers, while raw material dependence, energy mandates, and labor dynamics are woven into the discussion of procurement and investment timing. Altogether, the report equips capital equipment manufacturers, end-user engineering teams, investors, and supply chain strategists with the insight needed to align product roadmaps, capacity planning, and vendor evaluation with the market's actual trajectory.
Accessing the Full Intelligence Framework
The forging presses market is entering a phase where strategic advantage will belong to organizations that can read technological signals, interpret demand shifts, and time capital decisions accordingly. This research is designed to provide that capability. It offers the depth required to support rigorous internal analysis and the structural clarity necessary to translate findings into operational planning. For leaders seeking comprehensive segmentation data, detailed company profiles, full forecast breakdowns, and integrated scenario analysis, the complete report is available for review. Access the full publication to equip your 2026 and beyond strategy with decision-grade market intelligence.
For detailed analysis of this topic, please visit the official page: Forging Presses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wind Turbine Blade Market Hits $29.34B in 2025, Projected 6.53% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Wind Turbine Blade Market: Strategic Imperatives for 2026 and Beyond
The global energy transition is no longer a speculative narrative; it is a capital-intensive reality reshaping infrastructure portfolios worldwide. At the heart of this transformation lies the wind turbine blade, a critical component that dictates efficiency, longevity, and ultimately the levelized cost of energy. As we move through 2026, industry stakeholders face a complex matrix of technological innovation, regulatory pressure, and shifting geographic demand. This article serves as an executive overview of our latest comprehensive market research, designed to equip strategic decision-makers with the intelligence required to navigate this evolving landscape.
Our analysis indicates that the market has sustained a robust growth trajectory over the past half-decade. Valued at approximately 21.38 billion USD in 2020, the sector expanded steadily to reach 29.34 billion USD by 2025. This historical performance underscores the resilience of wind energy investments despite macroeconomic fluctuations. Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with the market expected to surpass 45 billion USD by the end of the decade. This growth is underpinned by a compound annual growth rate that reflects sustained demand for both onshore and offshore capacity, driven by national renewable targets and corporate procurement strategies.
However, top-line figures only tell part of the story. The strategic value for enterprise leaders in 2026 lies in understanding the underlying dynamics propelling this growth. Our report dissects the market into critical dimensions, offering a granular view of where value is being created and where risks are consolidating. For instance, the shift towards larger rotor diameters and higher capacity turbines is altering material requirements and supply chain logistics. Similarly, the geographic redistribution of manufacturing hubs is responding to trade policies and localization mandates. Decision-makers must recognize that the market is not monolithic; it is a collection of distinct segments, each with its own profit pools and competitive intensities.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of integrated turbine manufacturers and specialized blade suppliers. Our research identifies key players who are defining the standards for performance and sustainability. Companies such as LM Wind Power and Siemens Gamesa Renewable Energy remain pivotal, leveraging vertical integration and technological proprietary advantages to maintain market share. Vestas Wind Systems A/S continues to strengthen its position through strategic acquisitions, such as the recent expansion of its European manufacturing footprint, signaling a commitment to supply chain security and regional capacity.
Independent manufacturers like TPI Composites Inc. play a crucial role in the ecosystem, supporting multiple original equipment manufacturers across global facilities. Their ability to scale production, evidenced by significant production milestones reached in early 2025, highlights the importance of flexible manufacturing capabilities. Meanwhile, regional players in Asia and Europe, including Nordex SE, Enercon GmbH, and specialized Chinese manufacturers, are increasingly influential in shaping local market dynamics. The report provides detailed profiles of these entities, analyzing their strategic moves, capacity expansions, and partnership networks.
Market concentration remains a key metric for assessing competitive risk. The data suggests a moderately concentrated landscape where a handful of firms control a significant portion of revenue. Understanding the balance between integrated OEMs and independent suppliers is essential for procurement strategies and partnership evaluations. Our analysis explores how these relationships are evolving, particularly in the context of technology licensing and manufacturing alliances.
Technology and Sustainability: The New Battleground
Sustainability is transitioning from a corporate social responsibility initiative to a core operational requirement. The European wind industry has implemented a self-imposed landfill ban on decommissioned wind turbine blades effective January 2026. This regulatory milestone mandates that 100% of blades must be reused, recovered, or recycled. This shift places immense pressure on material science and end-of-life management strategies. Vestas has been proactive in this arena, aiming for full blade circularity by 2030 through initiatives like the CETEC project, which focuses on chemical disassembly processes for epoxy-infused blades.
Technological innovation is also accelerating in manufacturing processes. Advances such as additive manufacturing for blade molds, demonstrated through collaborations between industry leaders and national laboratories, are reducing production times and enabling more complex geometries. These developments offer potential efficiencies in cost and lead time, which are critical for meeting the aggressive installation targets set by governments globally. Siemens Gamesa's introduction of new offshore platforms exemplifies the push towards larger, more efficient turbines that can capitalize on offshore wind resources.
The report delves deep into these technological trajectories, evaluating their commercial viability and impact on cost structures. We assess the readiness levels of various recycling technologies and the potential for material redesign. For investors and product planners, understanding the timeline for these technologies to reach commercial scale is vital for long-term asset planning.
Market Dynamics and Regulatory Environment
The regulatory landscape is becoming increasingly complex, influencing both market entry and operational compliance. Beyond the European landfill ban, there are growing calls for Europe-wide regulations affecting large composite nacelle components. These regulations aim to standardize disposal practices and encourage circular economy principles across the industry. Companies operating in or exporting to these regions must align their product lifecycles with these emerging standards to avoid compliance risks and reputational damage.
Worldwide Wind Turbine Blade Anti-Corrosion Coating Market
Supply chain resilience is another critical dynamic. Geopolitical tensions and trade policies are prompting a reassessment of manufacturing locations. The data shows significant variation in regional market sizes, with Asia Pacific representing a substantial portion of global revenue, followed by Europe and North America. Each region presents unique challenges regarding logistics, labor costs, and local content requirements. Our study provides a comparative analysis of these regions, helping stakeholders optimize their geographic footprint without exposing sensitive strategic details prematurely.
Furthermore, the interaction between policy incentives and market demand creates volatility that requires agile strategic planning. Government subsidies, tax credits, and renewable portfolio standards vary significantly by jurisdiction. The report maps these policy frameworks against market growth projections to identify high-potential markets and potential bottlenecks.
What This Report Delivers for Your Organization
This market research is not merely a data compilation; it is a strategic toolkit designed for C-suite executives, investment managers, and product strategists. The full report offers detailed segmentation analysis across multiple dimensions, allowing you to isolate specific growth vectors relevant to your business unit. We provide historical data series that establish a reliable baseline for forecasting, alongside forward-looking estimates that account for scenario variations.
Readers will gain access to comprehensive profiles of key market participants, including their strategic focus, recent developments, and competitive positioning. This intelligence is crucial for benchmarking, merger and acquisition due diligence, and partnership identification. The analysis of recent industry events, such as major production milestones and facility acquisitions, provides context for understanding current market momentum.
Importantly, the report addresses the operational implications of sustainability mandates. We evaluate the cost implications of recycling technologies and the potential for new revenue streams from blade repurposing. This perspective is essential for companies looking to turn regulatory compliance into a competitive advantage. The insights provided are intended to support capital allocation decisions, R&D prioritization, and supply chain optimization.
Conclusion: The Path Forward
As the wind turbine blade market matures, the window for strategic advantage narrows. Success in 2026 and beyond will depend on the ability to anticipate technological shifts, navigate regulatory complexities, and optimize global operations. The data indicates a clear upward trend in market value, but realizing this potential requires nuanced understanding and precise execution.
Wind Turbine Blade Market
Our full market research report provides the depth and granularity needed to make informed decisions. It moves beyond general trends to offer specific, actionable intelligence tailored to the needs of industry leaders. We invite you to access the complete study to unlock the detailed segmentation data, comprehensive competitor analysis, and strategic recommendations that will define your approach in this critical sector. The insights contained within are designed to empower your organization to lead rather than follow in the renewable energy transition.
For detailed analysis of this topic, please visit the official page: Wind Turbine Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Precision Gear Market Reaches $1.14B in 2025, Booms at 6.5% CAGR to $1.77B by 2032
By pmarketresearch, 2026-09-15
Precision at Scale: Navigating the High Precision Planetary Gear Reducers Market Through 2032
Executive Overview: A Market at the Intersection of Precision and Scale
The high precision planetary gear reducers market stands at a critical inflection point where mechanical engineering excellence meets accelerating industrial automation. As manufacturing ecosystems grow increasingly demanding in terms of torque density, positioning accuracy, and operational reliability, precision reducers have transitioned from peripheral components to mission-critical enablers of next-generation motion systems. This strategic intelligence briefing distills the core findings of our latest High Precision Planetary Gear Reducers Market research, offering decision-makers a structured foundation for capacity planning, technology roadmapping, and competitive positioning through 2032.
The market has demonstrated consistent expansion over the past half-decade, with assessed baseline valuations climbing from approximately 832 million USD in 2020 to a projected threshold near 1.14 billion USD in 2025. Forward-looking assessments indicate sustained momentum, with the market expected to reach roughly 1.2 billion USD in 2026 and continue its upward trajectory toward approximately 1.77 billion USD by 2032. The compound annual growth rate across the forecast horizon is estimated at 6.5 percent, reflecting a mature yet highly dynamic landscape where incremental efficiency gains, application diversification, and regional deployment shifts collectively shape demand curves. These figures represent aggregate market direction rather than isolated performance snapshots, underscoring the importance of segment-level intelligence for precise investment allocation.
Strategic Drivers Reshaping Demand Architecture
The underlying demand architecture for high precision planetary gear reducers is being reconfigured by three interlocking forces: automation intensity, precision tolerance escalation, and system integration complexity. Industrial motion control is no longer defined solely by load capacity; contemporary applications require reducers that maintain rigorous backlash thresholds, exhibit predictable thermal behavior under sustained duty cycles, and integrate seamlessly with servo architectures and digital control ecosystems. As servo-enabled automation platforms accelerate their penetration across discrete and process manufacturing, precision gear reduction has become a foundational requirement rather than an optional upgrade.
Parallel to this, the proliferation of advanced manufacturing infrastructure continues to elevate the baseline for mechanical accuracy. Updated transmission precision guidelines, including the 2024 revision of ISO 6336-1, now emphasize more stringent dynamic testing under thermal equilibrium conditions, establishing new benchmarks for validation, quality assurance, and supplier qualification. In this environment, organizations that rely on component-level uncertainty face heightened exposure to integration risk, warranty exposure, and production downtime. Understanding where precision requirements are tightening, and which engineering pathways are proving most scalable, is essential for supply chain resilience and product roadmap alignment.
Robot Joint Precision Reducers Market
Regional Demand Emergence and Competitive Reconfiguration
Demand dispersion across geographic markets is not uniform, nor is it static. Maturity, industrial mix, and capital investment cycles produce distinct regional demand signatures that influence volume absorption, pricing tolerance, and supplier localization strategies. Our analysis indicates that Asia Pacific currently anchors the largest share of market valuation, reflecting the scale of advanced manufacturing deployment, robotics integration, and industrial equipment production across the region. North America and Europe continue to represent structurally important markets, driven by high-value automation modernization, precision engineering ecosystems, and localized service expectations that reward reliability, responsiveness, and engineering support depth.
At the same time, Latin America and the Middle East and Africa are emerging as incremental growth theaters where industrial modernization programs, infrastructure investment, and re-shoring considerations are gradually expanding addressable demand. The strategic implication for global suppliers is not simply to chase aggregate volume, but to calibrate regional go-to-market models according to local application profiles, lead-time sensitivity, and after-sales service expectations. In practice, this requires differentiated assembly footprints, inventory positioning, and engineering localization strategies rather than a one-size-fits-all export approach.
Recent operational developments already illustrate how leading players are adapting to these regional realities. SEW-EURODRIVE, for example, has moved to establish local assembly capabilities for its P2.e planetary gear units in South Carolina, compressing lead times for cataloged ratios to as little as six weeks. Such localization actions are not merely logistical adjustments; they represent strategic commitments to service velocity, regional demand capture, and supply chain risk diversification. Meanwhile, Shanghai SGR Heavy Industry Machinery Co., Ltd. has used major industry exhibitions to showcase its N-series planetary gear reducers, emphasizing alloy steel formulations, multi-planetary load distribution design, and targeted applications in new energy yaw and pitch control systems. These releases reflect broader market trends in which precision transmission components are increasingly tied to new energy infrastructure, heavy automation, and specialized motion platforms.
Technology Roadmapping and Application Complexity
Within the broader market, product differentiation is increasingly defined by precision class, gearing architecture, and suitability for specific motion profiles. Right angle and linear planetary gear reducer families both command substantial market relevance, but their value propositions diverge across application scenarios. Right angle configurations remain critical where spatial constraints and shaft orientation requirements dictate compact torque transfer, while linear planetary designs are increasingly favored in precision actuation and positioning workflows that demand repeatable motion accuracy and predictable load distribution.
Industry stakeholders must also recognize that application diversity is not merely a segmentation detail; it is a strategic signal. Robotics remains one of the most prominent demand centers, where high precision planetary gear reducers enable torque control, joint accuracy, and compact packaging for increasingly capable manipulator systems. Industrial manufacturing continues to drive broad-based demand through CNC machine tools, packaging equipment, conveyors, and material handling automation. Semiconductor equipment represents a more specialized but strategically important application corridor, where ultra-clean environment compatibility, rigidity, and micron-level positioning control can determine end-equipment performance. Additional application domains further extend the addressable base, spanning medical device manufacturing, specialized automation platforms, and precision test and measurement systems.
The strategic insight for procurement, R&D, and product management teams lies in mapping these application requirements to the correct precision tier and mechanical configuration. Over-specifying where tolerance requirements are moderate erodes margin, while under-specifying in high-precision workflows creates integration fragility. Our research examines how leading engineering teams are aligning specification decisions with real duty cycles, thermal load scenarios, and lifecycle cost models rather than nominal catalog values alone.
High Precision Planetary Gear Reducers Market
Competitive Intensity and the Imperative of Differentiation
The competitive landscape for high precision planetary gear reducers is shaped by a concentrated but heterogeneous set of manufacturers, each pursuing distinct differentiation pathways. Europe remains home to several influential engineering-led suppliers, including Neugart GmbH, Wittenstein SE, SEW-EURODRIVE, and Stober Antriebstechnik GmbH, all of which emphasize low-backlash performance, high rigidity, and application-tailored design philosophies. NEUGART's Economy and Precision Line series, for instance, reflect a dual-track strategy that serves both cost-sensitive motion control deployments and applications requiring elevated precision. WITTENSTEIN's portfolio, spanning low-backlash servo gearboxes and hygienic-design variants, illustrates the market's need for specialized configurations in demanding operating environments. SEW-EURODRIVE continues to extend its industrial and servo offerings with high-torque planetary gear units, reinforcing its positioning in heavy-duty automation contexts.
In the Americas and Asia, competitive dynamics are increasingly defined by integration capability, servo application specialization, and scale-driven precision manufacturing. Apex Dynamics Inc. has built a reputation around helical gearing approaches that deliver low backlash and high torque in servo applications, while Harmonic Drive LLC has advanced zero-backlash performance concepts that align closely with robotics and precision actuation requirements. Sumitomo Heavy Industries and Nidec-Shimpo contribute complementary strengths in integrated drive technologies and compact motion control, respectively. In China, the competitive field includes Shanghai SGR Heavy Industry Machinery Co., Ltd., Hubei Planetary Gearboxes Co., Ltd., and Ningbo ZhongDa Leader Intelligent Transmission Co., Ltd., each targeting precision automation, industrial robotics, and intelligent transmission system development through localized engineering resources and expanding manufacturing capabilities. ZF Friedrichshafen AG, meanwhile, applies transmission heritage to precision planetary gear reducers across automotive and industrial contexts, highlighting the cross-pollination of engineering competencies across end markets.
Market structure analysis indicates that the top three players account for approximately 25 percent of assessed market value, while the top five collectively represent roughly 35 percent. This level of moderate concentration suggests a market in which scale incumbents hold meaningful advantage, but where specialized differentiation, application expertise, and regional responsiveness still create viable pathways for competitive success. The practical implication is that competitive strategy cannot rely on volume positioning alone. Suppliers must simultaneously invest in precision consistency, engineering support, lead-time reliability, and application-specific validation to protect share and expand margin.
Regulatory and Standards Evolution as Strategic Context
Standards evolution and measurement rigor are becoming more consequential for commercial competitiveness. ISO 6336-1:2024 updates have introduced more demanding dynamic testing expectations under thermal equilibrium, directly affecting how manufacturers validate gear quality and how system integrators assess supplier reliability. In parallel, broader industry signals reinforce the scale of precision motion demand. Global industrial robot installations reached 590,000 units in 2023, and more than 62 percent of those installations incorporated high precision planetary gear reducers for torque control and precise motion. Servo-based automation adoption grew by 13.4 percent in 2024 according to VDMA reporting, while machine tool export performance in Japan exceeded 10.7 billion USD in 2023, signaling sustained global investment in precision manufacturing infrastructure.
For corporate strategists, these dynamics carry two implications. First, compliance and validation capability are increasingly part of commercial differentiation; suppliers that can demonstrate test rigor, thermal stability, and documented quality systems are better positioned in qualification processes. Second, macro demand indicators provide directional confirmation that precision transmission remains embedded in broader automation expansion, reinforcing the case for long-cycle planning rather than short-term transactional positioning.
What the Research Delivers for Strategic Planning
This High Precision Planetary Gear Reducers Market report is designed to support actionable decision-making across strategy, product management, sales planning, and supply chain leadership. Beyond aggregate market sizing and forecast trajectories, the study provides structured analysis that allows organizations to benchmark their strategic assumptions, refine segment targeting, and anticipate demand shifts with greater confidence.
The report examines market segmentation from multiple operational angles, giving readers clarity on how demand is distributed across type and application categories, where growth is most concentrated, and which structural factors are likely to influence share movement over time. It also provides regional analysis that contextualizes demand intensity, local manufacturing dynamics, and localization implications for suppliers seeking to optimize service models and inventory positioning. Competitively, the research profiles the strategic posture, engineering focus, and recent moves of leading participants, helping readers interpret not just who is active in the market, but how rivals are positioning themselves for sustained relevance.
In addition, the analysis incorporates recent corporate developments and industry context that shape near-term market behavior. Trade show activity, local manufacturing expansions, standards revisions, and robotics and automation demand indicators are integrated into the narrative to help stakeholders connect strategic planning with on-the-ground developments. The objective is to provide a usable intelligence base for capacity planning, market entry evaluation, supplier selection, pricing strategy, and product roadmap alignment.
Recommended Strategic Actions for 2026 and Beyond
As organizations move from market awareness to action, several strategic priorities emerge. First, firms should strengthen precision validation and thermal-performance documentation to align with evolving standards expectations and integrator qualification requirements. Second, regional service models should be revisited in light of lead-time sensitivity and localized assembly trends, particularly where rapid delivery and application support are becoming competitive differentiators. Third, application-specific engineering engagement should be deepened, because value capture increasingly depends on matching reducer configuration to actual duty cycles, not catalog optimization alone.
Fourth, competitive positioning should account for moderate market concentration by balancing scale efficiency with differentiated expertise in key application areas such as robotics, industrial manufacturing, and precision equipment. Fifth, organizations should use forecast visibility through 2032 to inform investment pacing, ensuring that capacity, R&D, and go-to-market resources are aligned with the demand curve rather than reacting to it after the fact. In a market expanding toward a projected valuation approaching 1.77 billion USD by the end of the forecast period, disciplined strategic planning will separate durable participants from transient competitors.
Closing Perspective
The high precision planetary gear reducers market is not simply expanding; it is maturing into a more technically demanding, regionally nuanced, and competitively layered environment. Sustained growth at a 6.5 percent compound annual rate through 2032 signals continued relevance, but it also raises the bar for precision, reliability, localization, and engineering support. Organizations that treat precision reducers as strategic enablers rather than commodity components will be better positioned to capture value, reduce integration risk, and build durable supplier relationships across the automation ecosystem.
This intelligence briefing offers a high-level view of the terrain, but the full report provides the granular segmentation, regional valuations, application-level breakdowns, competitive benchmarking, and forecast scenarios necessary for precise strategic execution. For leadership teams seeking to translate market direction into operational decisions, the complete analysis can be accessed through the source report page, where the full dataset, detailed segmentation insights, and company-level assessments are available for review.
For detailed analysis of this topic, please visit the official page: High Precision Planetary Gear Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nitrogen Gas Springs Market to Grow 5.7% CAGR, Reaching $657.3M by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in a Pressurized Market: The 2026 Nitrogen Gas Springs Industry Outlook
The industrial tooling landscape is undergoing a period of significant recalibration. As manufacturers navigate post-pandemic supply chain realities, shifting regulatory frameworks, and the relentless push toward Industry 4.0 integration, the nitrogen gas spring market has emerged as a critical focal point for operational efficiency and capital allocation. At PW Consulting, we recognize that understanding this market requires more than surface-level trend tracking. It demands a granular, forward-looking analysis that translates macroeconomic signals into actionable strategic directives.
Nitrogen Gas Springs Market
Our latest comprehensive market research publication, launched to support enterprise decision-making throughout 2026 and beyond, delivers precisely that capability. This article serves as a strategic primer, outlining the analytical architecture, competitive intelligence framework, and operational dynamics that define the study. We will examine why this research represents a critical asset for procurement leaders, strategic planners, and market expansion teams operating in the precision tooling sector. For executives who require the complete quantitative matrices, regional breakdowns, and deep-scenario modeling, the full report is available for immediate access through our research portal.
The Grand Trajectory: Mapping the 2026–2032 Forecast Horizon
The nitrogen gas springs market has demonstrated remarkable resilience and structural growth over the past half-decade. Drawing upon a rigorous historical dataset spanning 2020 through 2025, our analysis captures the full arc of market evolution—from the contraction pressures observed in 2021, through the steady recovery and expansion that defined the mid-to-late 2020s. By the close of the base year, the market had firmly established a momentum baseline that positions it for sustained appreciation across the forecast horizon.
Our forward-looking projections extend through 2032, charting a clear upward trajectory that underscores the sector's fundamental attractiveness. The compound annual growth rate anchored at 5.7 percent reflects a mature yet dynamically expanding ecosystem, driven by incremental adoption in precision stamping, injection molding, and advanced industrial machinery. Importantly, this growth narrative is not merely a linear extrapolation. It is the product of layered scenario modeling that accounts for technological adoption curves, capital expenditure cycles in end-user industries, and the gradual normalization of raw material supply chains.
Revenue figures, denominated in USD millions, illustrate a market that has consistently scaled beyond the 400 million threshold in recent years and is positioned to surpass critical psychological and operational milestones in the coming years. The projection curve reveals acceleration points that coincide with broader industrial modernization waves, particularly in regions where automation investment is reaching inflection. For strategic planners, these trajectory markers provide essential baseline parameters for capacity planning, supplier negotiations, and long-term inventory strategy. The complete temporal decomposition, including year-by-year variance intervals and sensitivity ranges, is fully detailed within the report's forecasting modules.
Architecture of the Analysis: What the Report Delivers
PW Consulting's market study is structured to function as an operational decision-support system rather than a static reference document. Every section has been engineered to address the concrete questions that arise during quarterly strategic reviews, M&A screening, and portfolio optimization exercises. The report's architecture encompasses several core pillars designed to give readers immediate tactical utility.
Granular Segment Mapping and Cross-Functional Overlay
The analysis disaggregates the market across multiple structural dimensions, allowing stakeholders to isolate performance drivers and identify high-yield opportunity corridors. Type-based segmentation traces the evolution of standard, compact, super compact, and micro nitrogen gas spring categories, examining how force ranges, footprint constraints, and application specificity are reshaping purchasing criteria. Application-level analysis evaluates demand concentration across automotive, aerospace, industrial machinery, and specialty sectors, highlighting where production volume aligns with margin expansion potential.
Regional demand architecture is similarly decomposed, mapping consumption intensity, growth velocity, and supply chain proximity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. By avoiding simplistic aggregation, the report enables readers to assess regional attractiveness through a multi-factor lens that weighs industrial base maturity, regulatory exposure, logistics complexity, and competitive saturation. All quantitative splits, share distributions, and absolute valuation figures for each segment and sub-segment are exclusively available in the full data appendix.
Gas Spring Market
Competitive Intelligence and Strategic Positioning Frameworks
The competitive landscape section moves beyond roster enumeration to deliver actionable profiling of the market's leading participants. Each profiled enterprise is evaluated across capability depth, geographic footprint, product architecture, innovation cadence, and commercial positioning. The analysis situates players within a broader competitive topology, identifying where scale advantages, technological differentiation, or distribution reach create defensible market positions.
Among the organizations subjected to this detailed scrutiny are DADCO Inc., Special Springs s.r.l., Hyson Products Inc., Pascal Engineering Corporation, KALLER, Bordignon S.r.l., Isotech Inc., Gemini Gas Springs Inc., AZOLGAS, and FIBRO GmbH. The report examines how each entity constructs its value proposition, responds to segment-specific demands, and navigates the tension between standardized catalog offerings and custom engineering engagements. For readers evaluating partnership opportunities, benchmarking their own positioning, or assessing acquisition targets, this competitive mapping provides an essential reference framework. The full profile set, complete with capability matrices and strategic assessment summaries, is contained in the proprietary competitive intelligence section of the report.
Competitive Landscape and Innovation Vectors
The nitrogen gas springs market is characterized by a moderately concentrated structure, with the top three participants collectively commanding a significant share of total revenue and the top five firms consolidating an even larger portion of industry output. This concentration pattern reflects the capital intensity of manufacturing, the importance of certification compliance, and the value that end-users place on supply reliability and technical support. At the same time, the presence of specialized domestic producers and niche innovators ensures that competitive pressure remains dynamic across both premium and cost-sensitive segments.
Innovation in this market is increasingly oriented toward digitalization, safety enhancement, and environmental resilience. DADCO Inc. garnered attention in early 2025 with the introduction of an IoT-enabled nitrogen gas spring series featuring integrated pressure and temperature monitoring, explicitly designed to support Industry 4.0 die tooling architectures. This move signals a broader industry shift where gas springs are no longer viewed merely as passive mechanical components but as intelligent nodes within connected manufacturing systems. The ability to monitor performance in real time, predict maintenance intervals, and optimize press cycles represents a tangible value-add that forward-looking OEMs are beginning to mandate.
On the safety and durability frontier, Special Springs s.r.l. advanced its product portfolio through multiple strategic updates throughout 2025. The launch of the Skudo-Flex accessory addressed cylinder longevity and operational safety in heavy-duty stamping environments, while the subsequent release of a new US Series catalog and an enhanced reducer component expanded the firm's capacity to perform in contaminated operating conditions. The company also rolled out a Fair Kit initiative to strengthen its trade exhibition presence, reinforcing its commitment to direct market engagement and customer education. These initiatives illustrate how sustained R&D investment, catalog expansion, and targeted commercial activation converge to build competitive moats.
Other market participants continue to differentiate through complementary vectors. Hyson Products Inc. maintains a full-line approach encompassing high-force configurations, slow-return variants, and contamination-resistant models tailored to metal stamping dies and injection molds. Pascal Engineering Corporation emphasizes precision and safety in mini and standard gas springs for stamping and molding applications, serving manufacturers who prioritize component quality as a productivity multiplier. KALLER has carved out a distinct position with high-temperature variants engineered to withstand operating conditions up to 250°C, addressing the demands of hot stamping processes. Bordignon S.r.l. leverages decades of heritage—dating back to 1958—to compete on longevity, reliability, and incremental innovation in stamping and forming applications. Isotech Inc. and Gemini Gas Springs Inc. extend the competitive field with steel and stainless steel offerings and in-house manufactured lift supports that meet stringent industrial standards, respectively. Meanwhile, AZOLGAS provides extensive catalog breadth for metal stamping and multi-technology industrial use, and FIBRO GmbH supports time-sensitive procurement with an expansive standard catalog and central European warehousing that enables same-day delivery.
Together, these players illustrate a market where competitive advantage is derived from a blend of engineering rigor, application-specific customization, digital readiness, and supply chain responsiveness. For enterprises evaluating supplier selection or attempting to anticipate competitor moves, the report's competitive analysis section decodes these positioning strategies in detail.
Structural Dynamics and the Operating Environment
No market analysis is complete without a rigorous examination of the external forces that shape supply, demand, and compliance risk. The nitrogen gas springs sector operates within a regulatory and materials environment that directly influences product specifications, production economics, and market access.
Regulatory Architecture and Standards Compliance
The standards landscape for nitrogen gas springs is defined by a cohesive set of international and regional requirements that establish baseline expectations for safety, performance, and interchangeability. ISO 11901-5:2021 specifies that nitrogen is the exclusive gas permitted for charging gas springs in stamping die applications, mandating commercial-grade nitrogen in purity class 5.0. This standard, alongside the broader ISO 11901 framework governing dimensions, forces, and safety instructions for press tools and dies, creates a harmonized technical baseline that manufacturers must satisfy to operate in global markets.
In the European context, compliance with the Pressure Equipment Directive (PED 2014/68/EU) remains mandatory for nitrogen gas springs deployed in machinery and tooling applications. Additionally, mounting dimensions and interchangeability specifications are shaped by VDI 3003 and CNOMO standards, which define mechanical interfaces critical to industrial stamping operations. These regulatory and standards-driven requirements function as both a barrier to entry and a quality signal, reinforcing the market position of firms that have invested in certified production processes and comprehensive documentation capabilities. The report's dynamics section examines how compliance costs, certification timelines, and standards evolution influence competitive accessibility and regional market entry strategies.
Raw Material Volatility and Cost Transmission
The economics of nitrogen gas spring manufacturing are materially influenced by steel price dynamics. Supply chain disruptions, geopolitical tensions, and demand-side fluctuations continue to inject volatility into raw material markets, with direct consequences for production costs and margin stability. Firms that maintain diversified sourcing strategies, forward-contracting arrangements, or value-engineered material specifications are better positioned to absorb cost shocks without eroding competitiveness. The analysis explores how cost transmission mechanisms vary across product categories and customer segments, and how procurement strategy can be aligned with broader market timing to optimize input cost exposure. Detailed cost-structure benchmarks, sensitivity coefficients, and sourcing scenario evaluations are provided in the full report's operational economics modules.
Strategic Implications for 2026 Decision-Makers
Translating market intelligence into executable strategy requires connecting high-level trends to organizational capabilities and constraints. For executives operating in or adjacent to the nitrogen gas springs market, several strategic imperatives emerge from the evidence base assembled in this study.
First, the growth trajectory and segment dynamics suggest that disciplined portfolio allocation will outperform undifferentiated expansion. Firms that map their product and service offerings to the application and type segments demonstrating the strongest alignment between demand growth, margin potential, and competitive accessibility will be best positioned to capture disproportionate value. The report's segment-level decomposition provides the diagnostic foundation for such allocation decisions.
Second, the competitive landscape analysis underscores the enduring importance of differentiation in a moderately concentrated market. While scale and distribution provide baseline advantages, sustained leadership increasingly depends on targeted innovation, whether in digital monitoring capabilities, high-temperature performance, contamination resistance, or rapid fulfillment infrastructure. Companies that treat product architecture as a strategic variable rather than a static attribute will uncover opportunities to premiumize their offerings and deepen customer lock-in.
Third, regulatory and materials dynamics introduce both risk and opportunity. Companies that proactively align their engineering and compliance functions with the evolving standards environment reduce the likelihood of market access disruptions and position themselves as trusted partners to risk-averse end-users. Simultaneously, effective raw material management—through supplier diversification, inventory optimization, and design-for-cost initiatives—can transform input volatility from a margin threat into a competitive differentiator.
Finally, the industry's movement toward connected, intelligent tooling components signals that the definition of value in this market is expanding. The integration of monitoring, data capture, and predictive capabilities into nitrogen gas spring products reflects a broader shift in which suppliers are expected to contribute to their customers' operational intelligence. Organizations that anticipate this shift and invest accordingly will be better positioned to capture the next wave of demand growth.
Accessing the Full Intelligence Package
This article has outlined the scope, methodology, and strategic relevance of PW Consulting's Nitrogen Gas Springs Market research, highlighting the structural trends, competitive dynamics, and operational considerations that will shape decision-making throughout 2026 and into the 2032 forecast horizon. The narrative presented here is intentionally high-level, designed to demonstrate the analytical rigor and practical applicability of the study while preserving the proprietary depth that delivers maximum value to our clients.
The complete report contains exhaustive year-by-year market sizing, detailed segment splits, regional revenue distributions, competitive capability matrices, scenario-based forecasts, and operational benchmarking data. Every quantitative insight referenced in this overview, along with granular sub-segment performance indicators and strategic recommendation frameworks, is fully documented within the publication. For procurement executives, strategy directors, market analysts, and investment professionals who require the full evidentiary base to support capital allocation, supplier negotiation, and market entry decisions, the complete report is available for immediate access. We invite you to consult the full intelligence package to ensure your 2026 planning is grounded in the most comprehensive and strategically actionable market analysis available.
For detailed analysis of this topic, please visit the official page: Nitrogen Gas Springs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Educational Toys Market to Hit $48.23 Billion by 2032, 8.47% CAGR
By pmarketresearch, 2026-09-15
The Educational Toys Market: Strategic Intelligence for 2026 and Beyond
The landscape of childhood development is undergoing a profound transformation, driven by shifting pedagogical priorities, technological integration, and an increasing recognition of play as a fundamental vehicle for learning. For executives navigating the consumer goods and education sectors, the Educational Toys Market represents not merely a niche segment but a critical battleground for future growth. As we move through 2026, the decisions made today regarding product portfolios, supply chain resilience, and compliance frameworks will determine market leadership over the next decade.
PW Consulting is pleased to present our comprehensive market research report on the Educational Toys Market, designed to equip stakeholders with the actionable intelligence required to capitalize on emerging opportunities. This analysis provides a rigorous examination of market trajectories, competitive pressures, and regulatory shifts that define the current operating environment from 2026 through 2032.
Market Trajectory and Macro Dynamics
Understanding the broader economic footprint of the Educational Toys Market is the first step in strategic planning. Historical analysis reveals a sector characterized by steady, resilient expansion. Between 2020 and 2025, the market exhibited robust growth, with revenue climbing from 19.2 Billion USD to 27.24 Billion USD. This trajectory underscores the increasing willingness of parents, educators, and institutions to invest in products that blend entertainment with developmental outcomes.
Looking forward, the forecast period from 2026 to 2032 projects continued upward momentum. The market is expected to reach 29.13 Billion USD in 2026, accelerating towards 48.23 Billion USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 8.47%, signaling a healthy expansion phase that outpaces many traditional consumer discretionary categories. For strategic planners, this indicates sustained demand elasticity, provided that products align with evolving consumer expectations regarding safety, educational efficacy, and digital integration.
However, raw growth figures only tell part of the story. The structure of this growth is fragmented across diverse product types, application scenarios, and geographical regions. While aggregate numbers suggest optimism, the distribution of value across these segments reveals distinct strategic priorities. Certain application areas are already demonstrating higher revenue concentrations, suggesting where consumer spending is most heavily directed, while regional variances highlight differences in market maturity and regulatory environments. Identifying which specific categories are driving the bulk of this expansion requires a granular analysis that goes beyond top-line estimates.
Report Scope and Operational Utility
Our report is structured to move beyond theoretical market sizing and provide practical tools for business decision-making. The analysis covers a historical window from 2020 to 2025 to establish baseline trends, followed by a forecast period extending to 2032. This longitudinal view allows organizations to distinguish between temporary pandemic-era anomalies and structural shifts in purchasing behavior.
The research encompasses a detailed segmentation analysis across three primary dimensions: product types, application contexts, and regional markets. By dissecting the market along these axes, we enable clients to identify high-potential niches that may be obscured in aggregate data. The report examines the specific revenue contributions of categories ranging from motor skills and arts and crafts to STEM-focused products and role-play instruments. Similarly, the application landscape is analyzed to distinguish between early childhood development needs, formal school curriculum integration, and other usage scenarios. Regional breakdowns further clarify where growth is most pronounced, allowing for targeted geographic expansion strategies.
A critical component of this research is the evaluation of market concentration. Current metrics indicate that the top three players hold a 30.0% share of the market, while the top five control 40.0%. This level of concentration suggests a moderately consolidated landscape where dominant incumbents wield significant influence over pricing, distribution, and brand perception. However, the remaining market share is distributed among a diverse array of specialists and innovators, creating opportunities for agile entrants who can differentiate through niche expertise or technological innovation.
To ensure the highest level of strategic utility, the report incorporates profiles of key market participants. These profiles examine the specific educational offerings, product portfolios, and strategic positioning of leading companies. By understanding the strengths and focus areas of competitors such as major construction toy specialists, interactive electronics manufacturers, and STEM curriculum providers, organizations can better anticipate competitive moves and identify gaps in the market.
Educational Toys Market
Competitive Landscape: Incumbents and Innovators
The competitive dynamics of the Educational Toys Market are shaped by a mix of legacy toy giants and specialized educational technology firms. Each player brings a distinct value proposition, ranging from mass-market brand recognition to targeted pedagogical solutions.
Among the established leaders, companies like Mattel, Inc. and The LEGO Group maintain strong positions by leveraging iconic brands and extensive distribution networks. Mattel offers a wide range of educational toys including construction sets, STEM learning products, and interactive play items. The LEGO Group, including its dedicated LEGO Education division, specializes in construction-based educational toys and STEM sets designed for scientific discovery and creativity. Notably, in January 2026, LEGO Education launched new STEM sets for children aged 7 and above designed to inspire curiosity, exploration, and scientific discovery, signaling a continued commitment to the older end of the youth demographic. Ravensburger AG also contributes to this competitive sphere, offering wooden puzzles, board games, and STEM building sets for cognitive development.
Hasbro, Inc. rounds out the major incumbent group with a focus on educational games, role-playing sets, and STEM-oriented toys for skill development. These large-scale players benefit from economies of scale and brand loyalty, but they also face pressure to innovate rapidly in response to technology-driven competitors.
On the electronics and interactive learning side, VTech Holdings Ltd. and LeapFrog Enterprises, Inc. are pivotal. VTech manufactures electronic learning toys, interactive tablets, and educational software for early childhood development. LeapFrog develops interactive electronic learning toys and books that combine technology with early education. In May 2025, LeapFrog showcased its latest collection of educational toys, including the Strum & Count Wooden Guitar, at Toy Fair 2025, highlighting a strategy that blends traditional tactile play with musical and cognitive learning. JAKKS Pacific, Inc. further complements this segment by manufacturing educational electronic toys and interactive STEM products.
The market is also seeing significant activity from specialized innovators. Osmo, Inc. offers interactive tablet-based educational games and learning kits for ages 3-11, bridging the gap between physical manipulatives and digital interfaces. MindWare, Inc. focuses on hands-on learning tools and manipulatives for science, math, and critical thinking, appealing to parents and educators seeking rigorous cognitive development tools. Spin Master Corp. provides STEM and interactive educational toys, including licensed educational lines, while Melissa & Doug, LLC specializes in wooden educational toys, puzzles, and open-ended play sets for preschoolers, catering to the demand for screen-free, age-appropriate products. Tomy Company, Ltd. from Japan develops educational construction toys, robotics, and STEM learning products, adding a strong international dimension to the competitive field.
Recent developments underscore the pace of innovation and the need for vigilance. In October 2025, STEMPlay Labs launched Wonder Briks and PictoMath, patent-pending construction bricks and math tools for STEM play, demonstrating how new entrants are targeting specific learning outcomes with proprietary technology. More recently, in May 2026, Smart Kids Planet expanded its age-specific STEM and educational toy lines for children ages 1-13 to align with modern developmental needs, reflecting a trend toward granular age segmentation. Conversely, regulatory scrutiny remains high. In March 2026, ZMC Group recalled multiple light-up toys due to battery ingestion hazards violating toy safety standards, a reminder of the operational risks associated with product safety compliance.
Regulatory Dynamics and Compliance Imperatives
For strategic planners, the regulatory environment is as critical as market demand. The Educational Toys Market is subject to stringent safety and quality standards that vary significantly across jurisdictions and are currently undergoing substantial updates.
In the United States, the Consumer Product Safety Commission (CPSC) has taken decisive action. On December 12, 2025, the CPSC published its final rule on Safety Standard for Toys: Requirements for Water Beads. This rule takes effect on March 12, 2026, and holds particular significance because it codifies requirements directly into 16 CFR Part 1250 rather than updating ASTM F963. This structural change implies a more rigid regulatory framework that manufacturers must integrate into their compliance systems immediately.
Across the Atlantic, the European Union has introduced the new Toy Safety Regulation 2025/2509, published on December 12, 2025. This regulation enters into force on January 1, 2026, and will apply fully on August 1, 2030. A standout feature of this regulation is the introduction of a digital product passport requirement for all toys, enhancing traceability and compliance. For companies operating in or exporting to the European market, this necessitates investment in digital infrastructure and supply chain transparency that goes beyond traditional labeling requirements. Failure to adapt to these requirements could result in significant market access barriers and reputational damage.
Educational Furniture Market
These regulatory shifts are not isolated events; they are part of a broader trend toward heightened consumer protection and ingredient transparency. Organizations must factor compliance costs, lead times, and potential reformulation needs into their product roadmaps. The interaction between rapid product innovation and rigorous safety testing creates a strategic tension that must be managed carefully to avoid recalls or market exclusion.
Strategic Imperatives for 2026 and Beyond
As the Educational Toys Market progresses through 2026, several strategic imperatives emerge for market participants. First, the divergence in growth rates across product types and applications demands a nuanced portfolio strategy. Companies cannot rely on a one-size-fits-all approach; instead, they must align product development with the specific developmental needs and purchasing behaviors of their target segments. Whether focusing on early childhood development, school curriculum integration, or other applications, the value proposition must be clearly articulated and substantiated.
Second, the competitive landscape requires continuous vigilance. The presence of both massive incumbents and agile innovators means that market share can shift quickly. Monitoring the product launches, patent activities, and strategic expansions of key players is essential for anticipating competitive pressure. The recent launch activities by LEGO Education, STEMPlay Labs, and Smart Kids Planet illustrate the diversity of innovation happening in real time, from new STEM sets for older children to patent-pending construction tools and expanded age-specific lines.
Third, regulatory compliance must be treated as a strategic capability rather than a back-office function. With the U.S. water beads rule already in effect and the EU digital product passport requirement looming, companies that proactively embed compliance into their design and manufacturing processes will gain a competitive advantage. This is particularly relevant for products involving electronics, small parts, or novel materials, where safety risks are heightened.
Finally, geographic strategy must account for regional differences in market maturity, consumer preferences, and regulatory frameworks. While some regions currently represent larger revenue pools, others may offer higher growth potential or less saturated competitive environments. Understanding the specific dynamics of North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa is crucial for optimizing market entry and expansion efforts.
Conclusion
The Educational Toys Market stands at a pivotal juncture, characterized by robust growth, intense competition, and evolving regulatory demands. The data indicates a market expanding from 27.24 Billion USD in 2025 to a projected 48.23 Billion USD by 2032, driven by a CAGR of 8.47%. However, realizing value in this environment requires more than awareness of these aggregate figures; it demands deep segmentation analysis, competitor intelligence, and a proactive approach to compliance.
PW Consulting's full market research report provides the detailed segmentation splits, regional revenue breakdowns, and granular application-level data necessary to construct a precise strategic roadmap. By accessing the complete report, organizations can uncover the specific growth velocities of individual product categories, identify the exact revenue contributions of each region, and benchmark their positioning against the detailed profiles of market leaders. We invite you to explore the full intelligence suite to ensure your 2026 decisions are grounded in comprehensive, actionable insight.
For detailed analysis of this topic, please visit the official page: Educational Toys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com